Vanuatu: Where Fintech Has to Cross an Ocean
The following is a fintech and wider digital economic development view of the US Pacific territory of Vanuatu.
In Vanuatu, the distance between a customer and their bank can involve more than a long drive. It might involve another island.
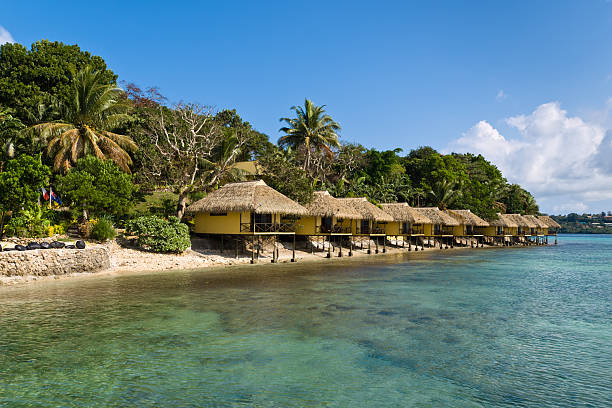
The Pacific nation consists of more than 80 islands, around 65 of which are inhabited, stretching hundreds of kilometres from north to south. Port Vila provides the country’s main financial and commercial centre, but much of the population lives in smaller communities where conventional banking infrastructure is considerably harder to provide.
That geography changes what fintech means. A mobile wallet is not simply more convenient than visiting a bank branch. For someone living on an outer island, it can provide access to financial services that would otherwise require significant travel.
Vanuatu is increasingly recognising that opportunity. Its National Financial Inclusion Strategy 2025-2030 places digital financial services at the centre of expanding access, while mobile money, regulatory experimentation and improvements to telecommunications infrastructure are gradually creating the foundations for a more connected financial system.
In Vanuatu, fintech has to solve a problem that technology companies in London or Singapore rarely encounter. The customer might literally be across the ocean.
Tourism matters, but so does what happens overseas
Vanuatu has a population of just over 300,000 and one of the smaller economies in the Pacific. Tourism traditionally provides an important source of income and employment, alongside agriculture, construction, services, fisheries and the public sector. Kava is an important agricultural export, while beef, copra and other products contribute to the rural economy.
Port Vila dominates financial services, with commercial banks operating alongside the Reserve Bank of Vanuatu and other financial institutions. But Vanuatu’s economy is also unusually connected to Australia and New Zealand through labour mobility.
Thousands of Ni-Vanuatu work temporarily overseas under seasonal and labour-mobility programmes, creating an important source of household income back home. That makes remittances particularly relevant to the fintech story. Sending money from Australia to a family member on another Vanuatu island should ideally be fast and inexpensive. Historically, geography and the cost of cross-border financial services have made that more complicated.
Mobile money provides one answer
One of the most established examples of digital finance is M-VATU, operated by Vodafone Vanuatu. The service allows customers to conduct financial transactions directly from their mobile phones, including transfers and other payments.
Importantly, M-VATU has also expanded into international remittances. Vodafone says more than 10,000 Ni-Vanuatu participate in Australia’s Recognised Seasonal Employer and related labour schemes, creating demand for easier ways of transferring earnings home. Its international remittance functionality allows money to be sent from Australia directly into M-VATU accounts.
That is a powerful use case for mobile money. A worker earning Australian dollars thousands of kilometres away can send money digitally to relatives who may themselves live far from a conventional bank branch. Fintech effectively shortens the distance at both ends of the transaction.
Financial inclusion now has another five-year plan
The Reserve Bank of Vanuatu (RBV) has made expanding that type of access a formal national priority. Its National Financial Inclusion Strategy 2025-2030 is organised around four pillars: digital financial services, micro and small and medium enterprises (MSME) finance, inclusive green finance, and financial education, capability and consumer protection.
Digital financial services come first for a reason. The strategy explicitly identifies Vanuatu’s dispersed population across 65 inhabited islands as a barrier to financial access and argues that digital financial innovation can help overcome some of those geographic limitations.
But the strategy also moves beyond simply opening accounts. Supporting micro, small and medium-sized businesses is another major priority, including improved financing for informal enterprises and businesses owned by women and young people.
That matters because Vanuatu’s economy contains enormous numbers of small businesses that will never resemble conventional corporate borrowers. Digital transaction histories and alternative financial products could eventually give lenders better ways of assessing them.
Climate finance is financial inclusion too

One part of Vanuatu’s strategy is particularly distinctive. It explicitly identifies inclusive green finance as one of its four pillars.
This makes sense in a country regularly ranked among the world’s most vulnerable to natural disasters. Cyclones, earthquakes, volcanic activity and rising climate risks can destroy homes, businesses and agricultural livelihoods with extraordinary speed.
Financial inclusion therefore cannot simply mean having somewhere to store money. People need savings, insurance, payments and eventually lending products that help them prepare for and recover from disasters.
Fintech could potentially make some of these products easier to distribute. Parametric insurance, for example, can use predetermined events such as wind speeds or rainfall measurements to trigger payments without relying entirely on lengthy conventional claims assessments.
Digital wallets could then provide another mechanism for getting emergency money to affected households quickly. In Vanuatu, climate resilience and financial inclusion increasingly overlap.
The regulator wants fintech companies to experiment
The RBV is also creating space for financial innovation. Its financial-inclusion framework now includes a National Regulatory Sandbox Guideline, providing a mechanism through which innovative financial products can be tested within a controlled regulatory environment.
The same regulatory framework includes dedicated operating guidelines for mobile-money service providers and a national financial consumer-protection policy. This is an important development for a small market.
Vanuatu does not need hundreds of fintech companies. It needs a smaller number of useful products capable of addressing practical problems such as remittances, rural financial access, small and medium enterprise (SME) financing and disaster resilience. A sandbox allows those products to be tested without pretending that a regulatory framework designed around conventional banks automatically works for everything new.
Better internet changes what fintech can accomplish
Digital finance still depends on connectivity. Vanuatu’s geography makes telecommunications infrastructure difficult and expensive to build, while redundancy is particularly important because natural disasters can damage critical networks.
The government is consequently investing in additional submarine-cable infrastructure. The planned Tamtam submarine cable, connecting Vanuatu with New Caledonia, is intended to provide additional international and domestic connectivity across Santo, Malekula, Efate and Tanna.
Crucially, it will provide backup capacity, improving resilience if another connection is disrupted.
The government is also developing new data-centre and broadband infrastructure following lessons from the major 2022 cyberattack that disrupted government systems.
Vanuatu’s wider digital strategy includes infrastructure sharing and the SMART Islands initiative, which aims to extend digital platforms and connectivity beyond the country’s principal urban areas.
For fintech, these projects are fundamental. A digital wallet is only useful when the network underneath it works.
The Pacific has another financial problem
There is nevertheless one threat that better domestic connectivity cannot resolve. Correspondent banking relationships have been disappearing across the Pacific.
Large international banks sometimes find relationships with small Pacific institutions commercially unattractive relative to the compliance costs involved. Losing those connections can make international transfers, trade payments and remittances more difficult.
The World Bank describes correspondent banking withdrawal as one of the region’s most urgent financial challenges. Vanuatu is therefore participating alongside Fiji, Kiribati, the Marshall Islands, Samoa, Solomon Islands, Tonga and Tuvalu in the Pacific Strengthening Correspondent Banking Relationships Project.
The eight countries each committed $9million from their International Development Association allocations to the regional initiative.
One of the most interesting proposals is a potential Pacific Payments Mechanism. Rather than requiring every small financial institution to maintain expensive international infrastructure independently, the proposed model could bring banks and non-bank providers onto a shared platform using common standards and services. For Vanuatu, that could eventually make cross-border finance considerably more efficient.
Cash will not disappear overnight
None of this means Vanuatu is about to become cashless. Cash remains important, particularly outside Port Vila and other larger population centres. Digital literacy, connectivity, affordability and trust continue influencing whether consumers actually use electronic financial services.
That explains why financial education and consumer protection form an entire pillar of the 2025-2030 inclusion strategy. The objective cannot simply be giving someone access to a mobile wallet.
People need to understand how to use it safely. That becomes particularly important as financial fraud and cybersecurity risks increase alongside digital adoption. Vanuatu’s transition therefore needs to happen at a pace that brings consumers with it.
Looking ahead
Vanuatu’s fintech opportunity comes directly from the things that make conventional finance difficult. Its population is small. Communities are dispersed across dozens of islands. Natural disasters are frequent, and remittances travel thousands of kilometres from workers overseas before reaching families at home.
Digital finance can reduce some of those distances. M-VATU shows how mobile money can connect overseas workers with households. The new financial inclusion strategy puts digital services and climate resilience firmly on the national agenda, while better submarine-cable infrastructure should make the underlying digital economy more reliable.
Vanuatu will probably never produce a fintech ecosystem resembling Singapore or Australia. It does not need to. For an archipelago spread across hundreds of kilometres of Pacific Ocean, success is much simpler: making sure that living on another island no longer means living outside the financial system.
The post Vanuatu: Where Fintech Has to Cross an Ocean appeared first on The Fintech Times.