Texas Turns Blue, Futures Turn Green: Why Wall Street Bought The Biggest Democrat Wave Since 1993
Texas Turns Blue, Futures Turn Green: Why Wall Street Bought The Biggest Democrat Wave Since 1993
Last night, America’s voters handed Trump the biggest midterm rebuke in a generation.
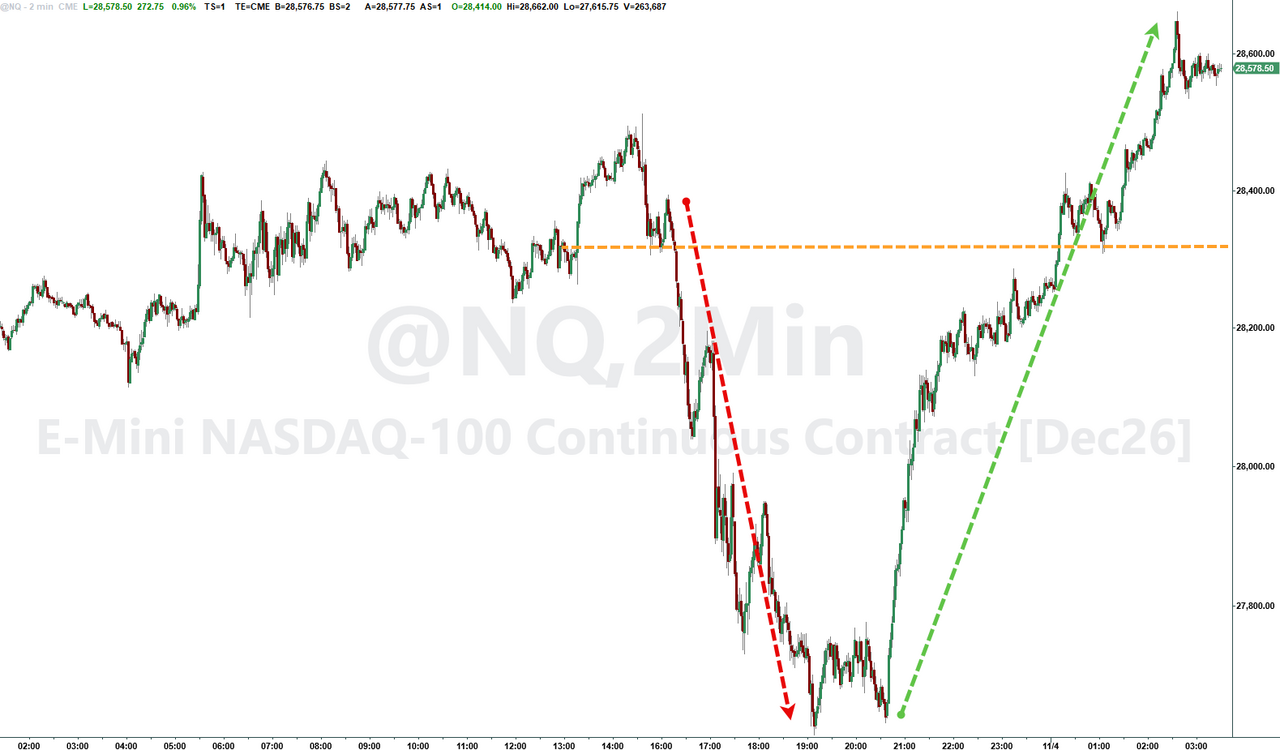
Then, a few hours later, Wall Street shrugged it off. Nasdaq futures, which had crashed as much as 2.4% as the blue wave turned into a tsunami, were up 0.9% by morning in New York, having ripped 929 points off the overnight lows. So the market’s reaction to Democrats taking both chambers of Congress, the Texas governor’s mansion and a Senate seat in Kansas for the first time since 1932 was… buy the dip.
Here is how it went down, from Michigan to the Rio Grande Valley, and why Goldman and Deutsche both think the morning-after rally has legs (for now).
Seven Flips, A Texas Earthquake And The First Muslim Senator
Democrats needed a net gain of four Senate seats. They got seven, winning races in Iowa, Kansas, Maine, North Carolina, Ohio, South Carolina and Texas, and beating several Trump-picked candidates along the way. The scorecard:
- Texas: James Talarico beat Ken Paxton to become the first Democrat elected to the Senate from Texas since 1988, despite Republicans vastly outspending him in the most expensive race of the cycle.
- Kansas: Megachurch pastor Adam Hamilton ousted Sen. Roger Marshall, giving the state its first Democratic senator since 1932.
- Maine: Troy Jackson unseated Susan Collins, ending her nearly 30-year run.
- Ohio: Sherrod Brown is back, beating Sen. Jon Husted.
- North Carolina: Roy Cooper beat Michael Whatley for Thom Tillis’s open seat.
- South Carolina: Annie Andrews beat Sen. Darline Graham, who presumably won’t be joking about heaven this morning.
- Iowa: Josh Turek beat Rep. Ashley Hinson, the call that clinched the majority.
Then there was Michigan, the one Democratic-held seat Republicans genuinely thought they could steal. Progressive Abdul El-Sayed, who ran on Medicare for All and taxing billionaires, beat former Rep. Mike Rogers 52.2% to 45.8% with about 93% of the expected vote in, per NBC, becoming the first Muslim ever elected to the Senate. He did it despite Haley Stevens’s last-minute defection to Rogers, and he signed off his victory speech with a blunt “Mike, enjoy your retirement!” His win “shows if Abdul can win in Michigan, progressives can win across the country,” said Ro Khanna, which is either a mandate or a warning, depending on which side of the aisle you sit.
Translation: what was supposed to be a coin-flip Senate turned into a rout. At last check Decision Desk HQ had Democrats at 54 seats to 44 (+7), with Alaska’s “Decoy Dan” contest and Mississippi still too close to call:
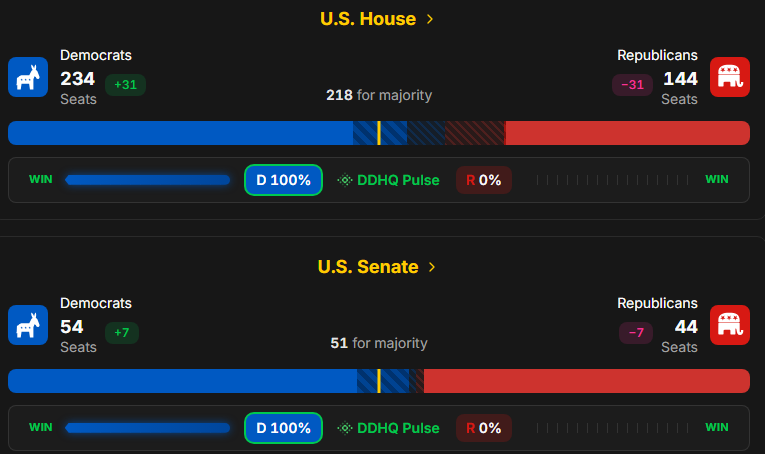
(chart source: Decision Desk HQ, via Goldman FX’s Jonathan Lightowler)
The Biggest House Majority Since 1993
The House was never really in doubt. The size of the margin was. NBC’s Decision Desk now projects Democrats will win about 258 seats, a number they haven’t reached since 1993, the year Bill Clinton took office, and that’s after Republicans spent a year and a half redrawing maps to give themselves a cushion. Gerrymandering at its finest.
The one thing Democrats won’t get is a veto-proof majority, which matters, because about an hour after telling the New York Times he was “absolutely willing to accept” the results and would “work with the Democrats,” Trump posted a hat with the word “veto” on it. He also argued Republicans would have won had he been on the ballot, and blamed… Fox News. Meanwhile Robert Garcia, in line to run House Oversight, issued a two-word statement for the White House: “Lawyer up.” So much for the beautiful bipartisan era.
Goldman’s co-head of FX research Mike Cahill, who doubles as the bank’s resident politics watcher, says the shape of the vote matters more than the headline:
Dems generally surpassing seat projections in what is now a clear ‘blue tsunami’ scenario. In many cases Dems are narrowly winning their ‘reach’ seats that Trump won by 10 and even 20 points… The pattern of the votes is much more Republican revolt + motivated Dems than progressives outperforming. Dems are winning in rural areas (including some places Trump won by 10-15pts) as well as suburban regions… looks like tariffs + gas prices (and ICE in south Texas for example) having a large impact.
Which leads to a counterintuitive conclusion: Cahill argues bigger majorities stuffed with moderates from red districts could actually mean less power for the progressive wing, not more. Then again, as he concedes, a number of those rural Democrats ran on AI regulation and ending data center subsidies, “in states like Texas and Ohio but also South Carolina, Kansas etc.” Which brings us to the Lone Star State.
Don’t Mess With Texas (Data Centers)
No race captured the night better than Texas, where Democrats won statewide for the first time since 1994.
DEMOCRAT HINOJOSA WINS TEXAS GOVERNOR RACE, CNN PROJECTS
— zerohedge (@zerohedge) November 4, 2026
Austin state Rep. Gina Hinojosa ousted Greg Abbott with roughly 53% of the vote, becoming Texas’s first Latina governor and the first Democrat in the office since Ann Richards. She did it despite Abbott’s campaign spending some $180 million since last year on what was supposed to be a safe fourth term (and tens of millions more from Elon Musk backing Republicans). Democrats also flipped lieutenant governor, attorney general and, yes, railroad commissioner, the office that regulates Texas oil and gas.
For markets, though, the money line came from Goldman. Here is Cahill again:
Abbott (the longtime Republican incumbent) had put a freeze on permitting new data center projects but the expectation was the freeze would likely be over by EOY at which point they would start working on the backlog/ issuing new permits. But Hinojosa said she will not lift the freeze until more comprehensive regulation is passed. That process could of course take much longer potentially pushing gigawatts that are supposed to come online in 2027 to 2028.
Regular readers know this has been coming. We warned back in May that electric bills could be the 2026 election shocker, and ahead of the vote we mapped the states where Tuesday’s midterms can pull the plug on data centers. Texas just pulled it. Data center names IREN, Hut 8 and Applied Digital all traded lower premarket, even as the hyperscalers bounced. Which, as we’ll see, is exactly the split Goldman’s Rich Privorotsky expects.
From Puke To Rip: The 900-Point Round Trip
Futures were already sliding as the first polls closed, and once Talarico took Texas and the House fell, they puked. At the lows, Nasdaq 100 futures were down 2.4% and S&P futures down 1.4%, while Korea’s KOSPI was down more than 4%. Tech took the brunt, for one simple reason that UBS summed up in real time:
“Markets are risk off and responding to the rising odds of a Blue wave, the implication being that there could be more friction around AI/data center investments, as well as more gridlock and negotiation/ bargaining around the debt ceiling and fiscal policy” – UBS
— zerohedge (@zerohedge) November 4, 2026
Then the selling just… stopped. By the time London walked in, NDX futures had already clawed back most of the drop (chart source: Goldman FX/Macro, Bloomberg):
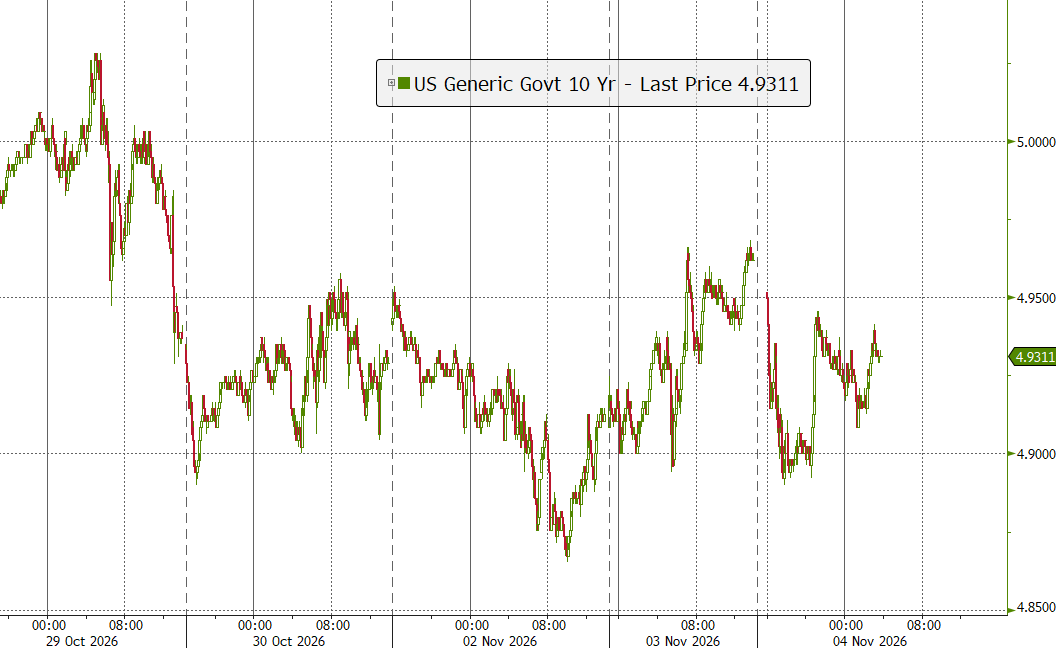
The safe-haven trade unwound alongside it. The 10Y yield tumbled as much as 7bps overnight, to around 4.89%, as traders bet gridlock means less spending, then round-tripped right back to roughly 4.93%, flat on the day by early London trading:
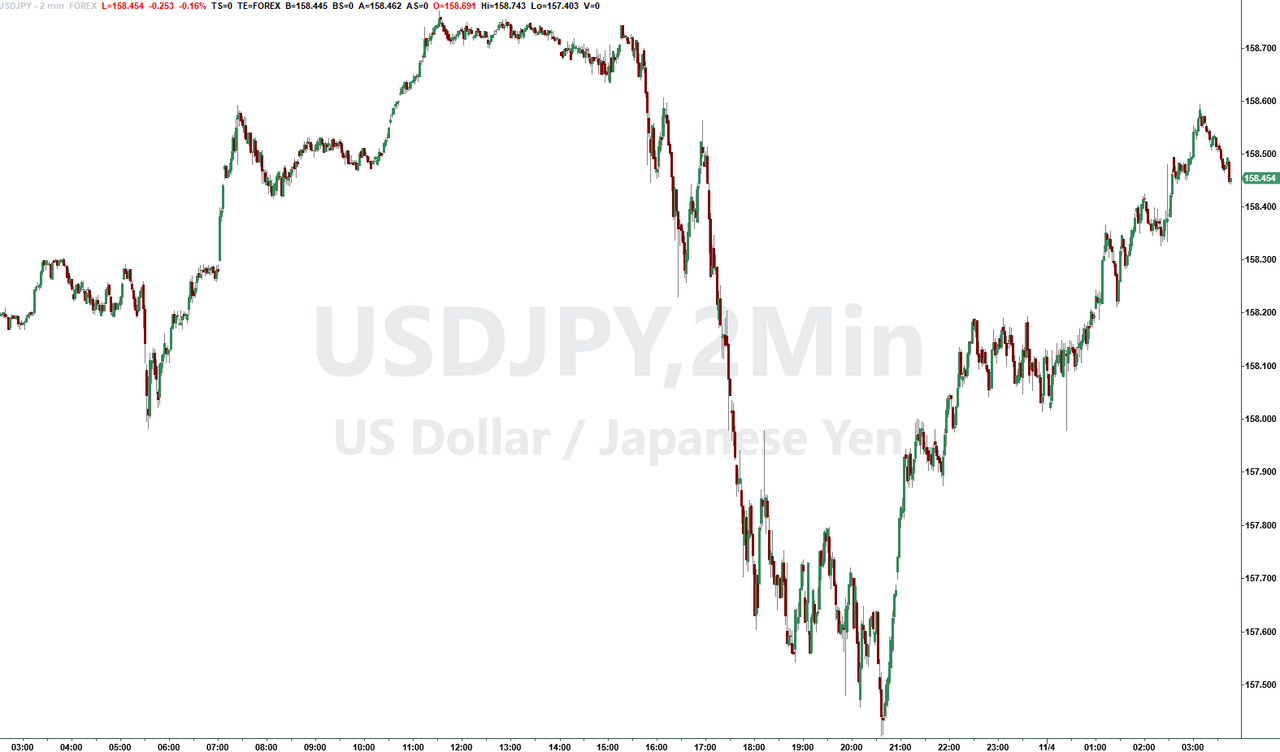
The dollar was the one move that stuck. The DXY slid and USDJPY dropped from above 158.70 to below 157.50 before bouncing, while Goldman’s Asia sales desk reported a “firm USD selling bias” led by macro hedge funds and CTAs.
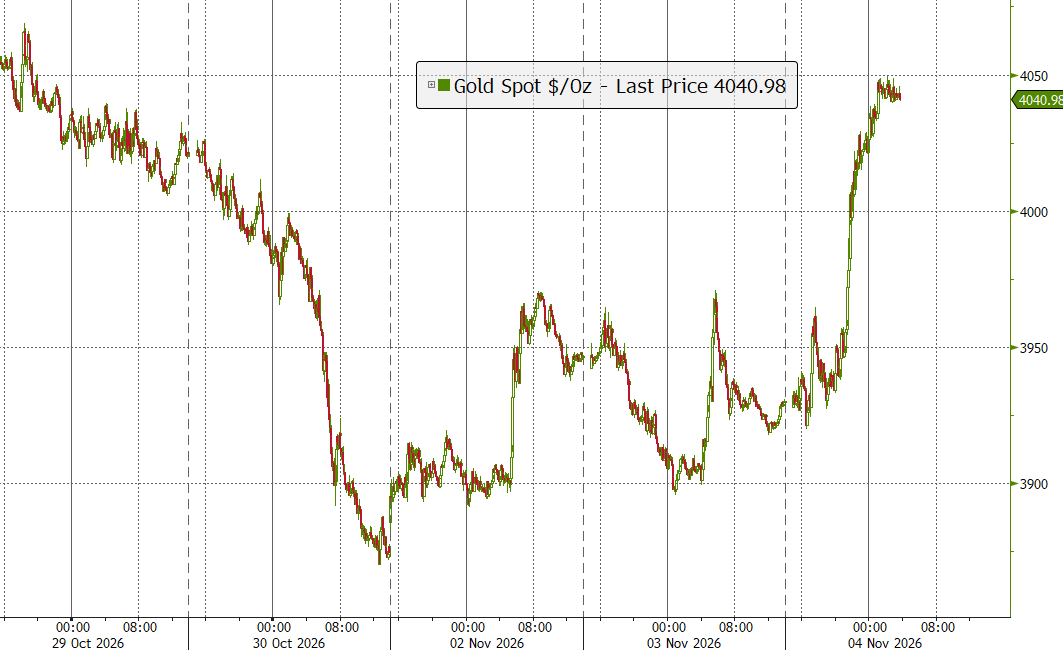
Gold jumped 2.3% to $4,020, because of course it did.
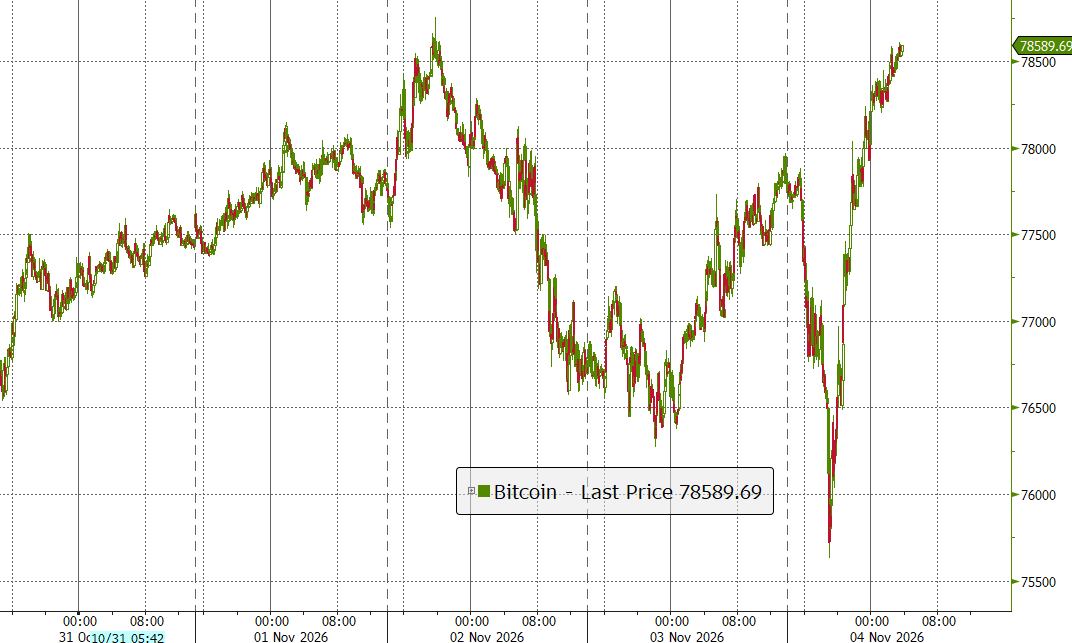
Bitcoin was back at yesterday’s highs…
By early morning in New York the reversal was complete: S&P futures up 1%, Nasdaq futures up 0.9% and Dow futures up 700 points, with AMD’s blowout quarter (+6% premarket) helping the AI bulls along.
So what happened? Goldman’s Rich Privorotsky, writing in his latest “GS Basics” note (available to pro subs), says the answer is positioning:
With legislative margins and key regional leadership races now decided, equity futures saw a sharp overnight dip followed by a meaningful recovery… Resilience is interesting. A lot of hedges were put on over the past few days that now need to be monetized. Multiples have already been aggressively de-rated, particularly across AI infrastructure, in anticipation of these concerns. The question is how much is already in the price? My suspicion is that vol will struggle to sustain a bid and the initial selloff gets absorbed as people begin picking apart what they actually want to own.
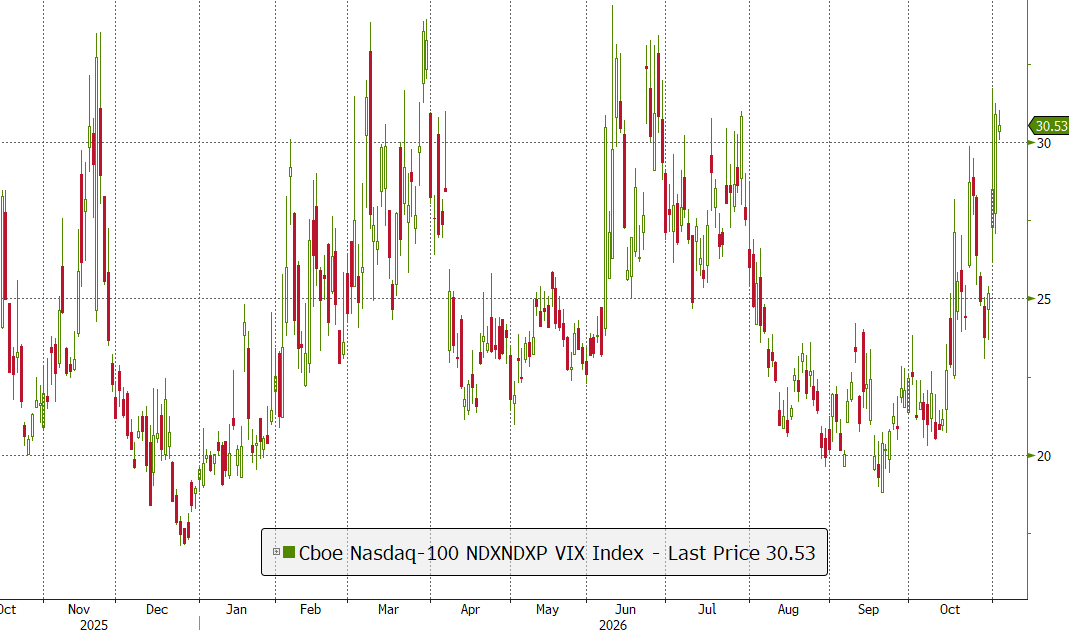
In other words, the event everyone hedged is over, and the hedges are now the fuel. Privorotsky flags that Nasdaq vol is still “quite elevated,” with the VXN at 30.5, not far off its March peak of 33.5:
And his closing call is about as unambiguous as a Goldman trader gets: “my gut is that AI infrastructure has been sold to death… Vol likely comes in quickly and that drives spot in the short term.”
The more interesting part of his note is what a Democratic crackdown on data center buildouts actually means. Privorotsky sees two very different implications from a constrained supply curve:
First, if you sell chips, cooling, electrical equipment or the nuts and bolts of data centers, there is a legitimate risk that customers have overordered relative to the capacity they can actually energize. Some of that demand could migrate to other geographies or BTM solutions, but not necessarily quickly enough… The second, more perverse implication is that compute itself becomes even scarcer. …If you can’t, the scarcity value of existing, energized compute should rise. That potentially benefits the hyperscalers and owners of deployed capacity… Ultimately, throttling the supply of compute doesn’t necessarily destroy demand… it could just push pricing higher for longer.
Put differently: owning energized compute today beats promising compute tomorrow. Hence hyperscalers up and data center developers down this morning. (And yet another reason to make “behind the meter” generation mandatory: you can’t freeze a permit you don’t need.)
Deutsche: “Risk Positive”… And It’s All About The Debt Ceiling Now
Echoing virtually every other sellside desk this morning, Deutsche Bank’s head of FX research George Saravelos also blessed the rebound. In his post-election note (also available to pro subs), he lays out three reasons:
1. Risk positive. We agree with the rebound in global equities and risky FX currencies overnight. The combination of a large Democratic majority in Congress and President Trump’s statement that he is willing to work with the opposition should act as a break on extreme policy outcomes and bring down risk premia. The market is increasingly likely to interpret surprising policy shifts from the Executive as time-bound by the next Presidential election or the new domestic political configuration.
2. No news is good news on Iran. Over the last 48 hours, President Trump stated that no attack on Iran is imminent and has acknowledged that the Iran war drove part of the election outcome… with oil flows through the Middle East having materially recovered, the market is pricing a large imminent risk premium of re-escalation and energy supply disruption. There is therefore negative time decay on the oil price, the more escalation is delayed, the bigger the downward pressure on oil.
3. All about the debt ceiling (and AI) now. The single biggest source of domestic policy uncertainty remaining in the US is the debt ceiling that will become binding by Q2 of next year. It is reported that Republicans aim to pass a debt ceiling increase via reconciliation over the next few weeks. If this succeeds, it will remove one additional layer of uncertainty on fiscal policy, while also preventing AI and other policy matters from getting bundled up in a protracted negotiation with a Democratic Congress. Irrespectively, question marks around the build-out of AI will likely persist.
His bottom line for FX: lower energy and policy risk premia plus higher AI implementation risk should “on balance weaken the dollar,” supporting “a continued bottoming out in EUR/USD.” And if the lame-duck Congress fails to lift the debt ceiling before January, Saravelos would consider it “an added dollar negative.”
Translation: Republicans have about eight weeks of unified control left to raise the debt limit on their own terms. Miss that window, and the first big fight of the new Congress is a debt-ceiling standoff with Hakeem Jeffries, the new House majority and an Oversight chair who has already told the administration to lawyer up. What could go wrong?
Gridlock Is Good… Until The Bills Come Due
The bulls have history on their side. As Privorotsky notes, “the S&P 500 has been higher 12 months after all 19 midterm election cycles since 1950,” and he argues that with Trump in place through 2028, CEOs now have every reason to pull capex, permitting and M&A forward into 2027 to lock in today’s rules:
I think the market will increasingly anchor on what happens in 2027 rather than trying to discount every possible outcome in 2029. Geopolitics remains the swing factor and could take us in either direction very quickly.
Fair enough, and the hedge unwind will probably carry stocks for a few sessions. But look at what actually survived the night: a Texas data center freeze that could push gigawatts into 2028, a debt ceiling that binds by Q2, an Iran war for which CENTCOM reportedly has a plan to strike as early as today, and a President who’s openly auditioning for “Mr. Veto.” None of that got priced out at 3am; it just got hedged and unhedged. Our bet is the morning-after melt-up is the easy part, and the hard part (permits, power and the debt limit) arrives on Capitol Hill in January.
Then again, nothing says “healthy market” like a 900-point rip powered by traders monetizing the hedges they bought for the very outcome that just happened.
Much more in the full Goldman “GS Basics” note and Deutsche’s post-election note, both available to pro subs.