Powell: Jeff Levine on Why Caring for Aging Parents Puts Retirement at Risk
Caring for an aging parent can be an act of love. But it can also come at a steep financial price, particularly for adult children who reduce their working hours, interrupt their careers, or stop saving for retirement to provide care.
The consequences can extend well beyond the cost of hiring a home health aide or paying for long-term care. Family caregivers may sacrifice earnings, career advancement, and their own financial security.
In a recent episode of “Focus on Finance Forum,” I spoke with Jeff Levine, chief planning officer at Focus Partners Wealth, about the financial challenges of caregiving and the steps families can take to prepare.
The following Q&A has been edited for length and clarity.
Why is caring for an aging parent so expensive?
Bob Powell: We’ve had a number of questions about the cost of caregiving. And a new AARP study on the subject, which found that caregivers age 18 and older spend an average of $11,508 a year on caregiving, gives me pause. How do people deal with what seems to be an insurmountable financial problem for many families?
Jeff Levine: It is an insurmountable problem for many. We’ve done a really good job of extending life expectancies through medicine in recent decades, but living longer comes with its downsides.
Living longer means we need to account for expenses over a longer period. And living longer doesn’t necessarily mean living healthier longer.
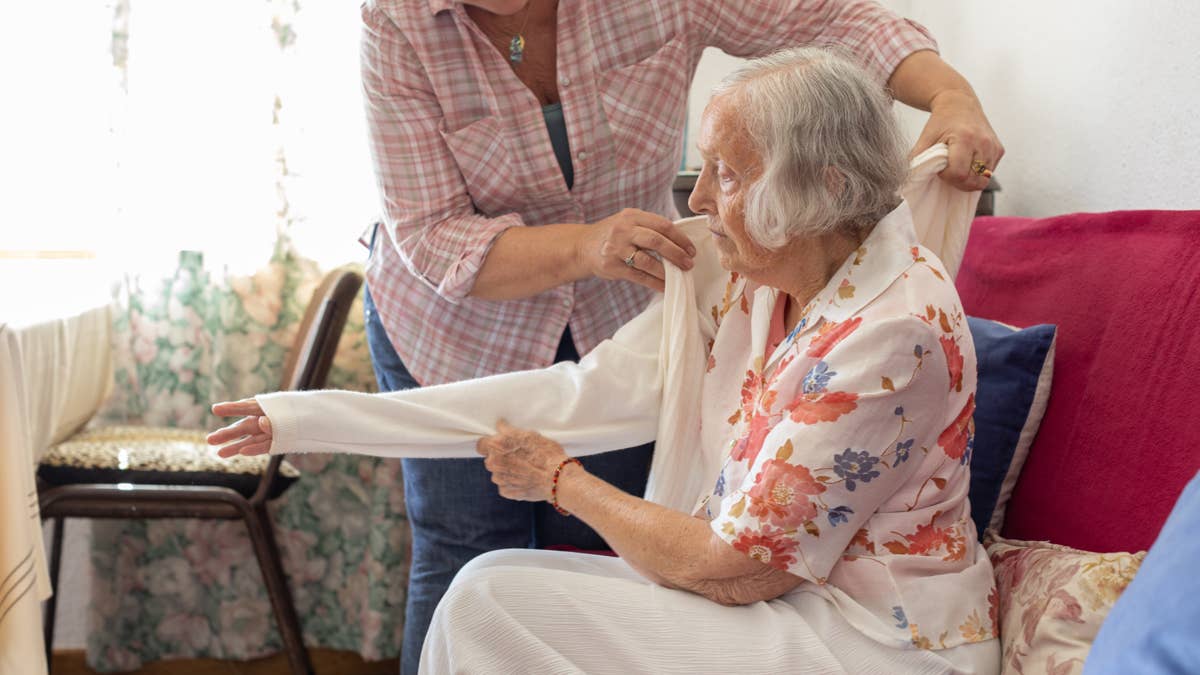
That could mean extended stays in long-term care or simply needing help with everyday activities. Getting dressed might be a challenge for some people. They can go on with their day after that, but every day, someone has to help them get dressed.
Who’s that going to be? Are we hiring someone to come do that? Is it a family member? The cost is high, no matter how you handle it.
Some people may look to insurance to help with long-term care expenses. Unfortunately, long-term care is not a great thing to insure.
Insurance works best when there’s a relatively small chance of something happening that has a high impact. But long-term care isn’t something that has a relatively small chance of happening. If you live long enough, the odds are that it will happen to you.
That can make long-term care insurance very expensive compared with other types of insurance.
But let’s say you don’t want long-term care insurance. You say, “I have a close-knit family, and we take care of our own.”
That’s great. I love the family altruism there. But that also comes with a cost.
There’s the time someone isn’t able to go to work. Even if they’re not paid by the hour, they may be distracted or have fewer opportunities for growth in their career.
Study after study shows a tremendous financial cost to family caregivers.
I’m not saying somebody shouldn’t do that. It’s your family. You want to support them in that way. What an amazing thing to do for someone you care about.
But it’s important to know that it’s probably going to have an impact on your personal finances.
How can caregiving put your own retirement savings at risk?
Powell: There’s something called the generosity paradox. You’re putting your own financial security at risk to care for an aging parent. You might be delaying retirement savings, stopping contributions altogether, or leaving the workforce.
How do you make up for what you lose financially?
Levine: There are a variety of ways to approach this, and personal finance is very personal.
It could be that you have a good sense that, at some point, you’re going to be the caretaker for your family. You might want to save more during your working years before that happens so you can afford to take that time off or retire early.
One approach is pre-funding, with the idea that at some point you’re going to take a financial hit.
What happens to your career if you leave work to care for a parent?
Levine: You also need to understand how taking a break will affect your career.
There are some jobs where you can be out of the workforce for two or three years and come back and pick up where you left off. There are other careers where [if] you’re gone for two or three years, you’re way behind. Everything has passed you, and it’s going to be very difficult to get a job.
So there’s a lot of planning involved.
Again, we’re not here to tell someone they shouldn’t take care of a loved one. That’s a personal choice. I can’t think of too many things that are more selfless and valuable.
But it’s really important to understand how that decision is going to affect you financially.
How can siblings share the financial burden of caring for aging parents?
Levine: Another possibility depends on the family. Maybe one child is taking on the caregiving responsibility, but there are several children.
There can be support arrangements where some of the children contribute financially to help the one who’s using their time and energy to take care of Mom or Dad.
That can work well in close-knit families.
Where can family caregivers find help, and how much should they sacrifice?
Levine: There are resources out there for individuals who have fairly modest means. One of the best things you can do is help a family member figure out what resources are available.
If people aren’t sure where to turn, there’s an organization called the Aging Life Care Association, where they can find someone local to help them think through these issues.
But the biggest thing to me is understanding how caregiving will affect you financially.
It’s great to say, “Well, it’s just money. Who cares?”
But at the end of the day, that financial stress can affect your own health. It can affect your family and the satisfaction you have in your marriage. These are all things that matter.
And when you’re taking care of a loved one, would that loved one want you to sacrifice all these things for them?
There’s no right or wrong answer. But understanding the impact across the board so you can make an informed decision is really the most important thing.
Related: Suze Orman says the biggest retirement asset hides a trap