Fintech Could Be Europe’s Next Strategic Advantage
When the European Union and Armenia held their first ever summit in Yerevan on 4 and 5 May, the language was political. Deeper ties, new trade, a strategic partnership with a country Brussels has courted for years.

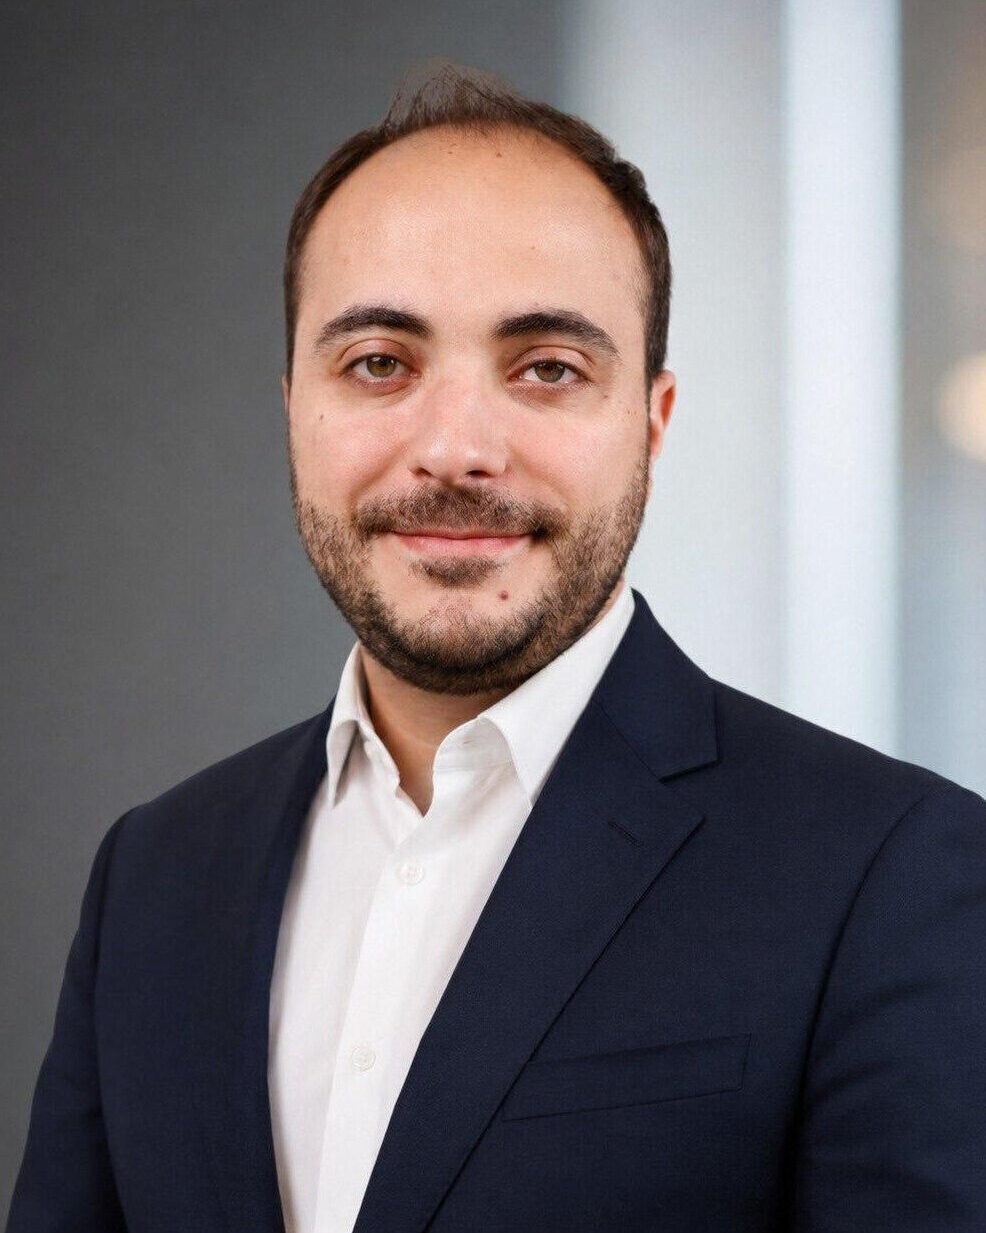
Vardan Khachatryan, chief executive of the Malta-licensed electronic money institution Fast Shift, argues that whether any of it turns into commerce depends on something far less ceremonial: the financial plumbing that has to carry the payments.
Vardan Khachatryan is chief executive of Fast Shift Limited, an electronic money institution authorised by the Malta Financial Services Authority and part of Armenia’s Badalyan Brothers Group. He was previously group chief legal officer at Fastex and is a co-founder of the Web3 Armenia Foundation. The views below are his own.
Global economies are competing for access to new commercial opportunities and racing each other on advanced technology. While that contest plays out in public, fintech firms are quietly connecting emerging markets to the European Union, and the EU to Armenia is the clearest current example.
Political agreements and new trade corridors expand access and attract investment. They also create demand for the infrastructure that has to support the cross-border activity they generate, and that is where the gap sits. The financial rails connecting these regions to Europe remain fragmented, which is a headwind for realising the potential of the corridors themselves.
For most of the past decade, European fintech competed on product speed. Who could launch the slickest app, offer the cheapest transfer, deliver the fastest onboarding. Compliance was treated as a costly back-office function rather than a driver of growth.
That is changing, and the supervisory numbers show it. Applications for payment services and e-money authorisation in Malta rose 43 per cent between 2022 and 2024, against a falling trend across most of the EU, according to a European Banking Authority peer review. The Malta Financial Services Authority recorded 1,849 supervisory interactions with authorised entities in 2025. Regulators across the bloc are becoming both stricter and faster, which means the firms that get governance right and treat licensing readiness as a commercial asset are the ones positioned to expand inside the EU and beyond it.
Fast Shift’s own authorisation is the case I know best. As part of an Armenian group, the company built its operations around serving international financial flows while meeting the requirements of an EU regulator. An MFSA approval is, in effect, evidence that a compliance framework assembled outside the EU can withstand scrutiny inside it. That is a signal of operational maturity, and it is not one that can be manufactured quickly.
The commercial case for building this now is concrete rather than theoretical. European Central Bank research published this year estimates that interlinking fast payment systems between two markets lifts bilateral trade by around 4 per cent, roughly half the boost that comes from a formal trade agreement. Celent, a GlobalData company, forecasts that SEPA Instant will account for 18 per cent of all euro payments by 2035. For firms trying to connect emerging markets to Europe, establishing compliant and interoperable infrastructure early is likely to determine who captures that growth as volumes rise.
Armenia shows the scale of what has been sitting untapped. Net cross-border transfers to individuals in the country reached 1.08bn US dollars in the first five months of 2026, against 511.7m dollars in the same period of 2025, according to the Central Bank of Armenia. That is more than double, from a diaspora spread across the globe.
Much of that demand is underserved, particularly for international enterprises and high-growth businesses trading with European counterparts and waiting to be paid by them. The result is higher costs and slower settlement than the frictionless standard of an intra-EU SEPA transfer, which is precisely the friction the new corridors are supposed to remove.
Against that backdrop Fast Shift is building the conduit: dedicated IBANs, SEPA and SEPA Instant integration and SWIFT support, with card issuance and merchant acquiring planned for 2027 as volumes grow. The aim is to give international enterprises, Armenian businesses and the diaspora direct and compliant access to European banking rails at a scale that has not existed before.
The pattern is worth watching well beyond Armenia. Across EU-adjacent, high-remittance, diaspora-linked markets, including the Western Balkans and parts of the Eastern Partnership, the same structural opportunity is emerging. Businesses and individuals increasingly need reliable cross-border payment access, while local financial infrastructure remains unevenly connected to European rails.
The fintechs best placed to capture that demand will be the ones that can combine local market access with EU-grade regulatory and payments infrastructure. Companies from emerging markets do not have to wait for financial systems to evolve around them. They can build the bridges themselves.
Financial infrastructure is the quiet engine of the global economy, invisible when it works and decisive when it connects emerging markets to global capital. As Europe builds new economic relationships with its neighbourhood, fintech will increasingly determine whether those corridors translate into real commercial activity. For firms able to bridge local markets and Europe’s regulatory and financial infrastructure, the opportunity is not simply to take part in the new corridors, but to help build them.
The post Fintech Could Be Europe’s Next Strategic Advantage appeared first on The Fintech Times.