BankiFi’s Hartley on Banks Becoming the SME Gateway
Small business customers rarely run their finances inside their bank. Invoicing sits in one application, bookkeeping in another, payments somewhere else again, and the bank holds the account at the end of it.

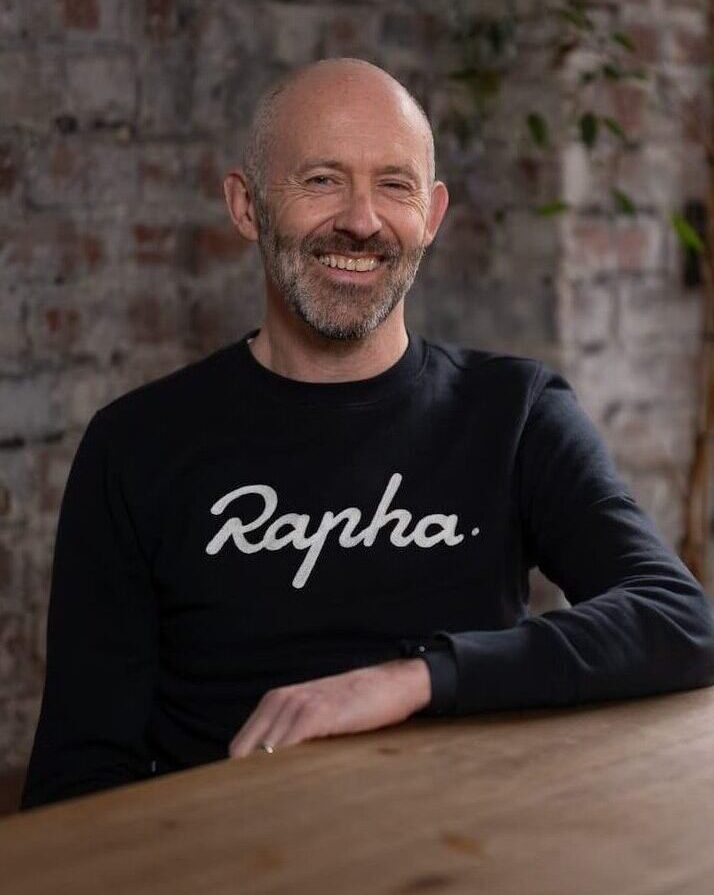
Mark Hartley, chief executive and founder of BankiFi, thinks that arrangement is what is costing mainstream banks their primary relationship with small and medium-sized enterprises. In written answers to The Fintech Times he argues the fix is not for banks to build the missing tools, but to embed other people’s.
BankiFi describes the change as a shift from bank to gateway. Asked what that looks like for a small business today, Hartley put it in terms of where the work happens. It means, he said, “giving small businesses access to everything they need to run their business from within their bank’s mobile and online banking platform”.
He cited JumpCloud research from 2025 which, he said, found that 51 per cent of UK SMEs use between five and ten different applications, while 83 per cent would prefer to access everything in one place. “The bank is the natural home for that because customers already trust it with their money and data,” he said.
“Checking balances and making payments is no longer enough,” Hartley added. “Businesses increasingly expect integrated workflows covering invoicing, payments, bookkeeping, cashflow and tax, all delivered through a single trusted experience. The bank becomes the gateway to running the business, not just managing the bank account.”
What changed, on his account, is expectation rather than technology. Business owners now want the same connected experiences they have as consumers, and open banking and real-time data sharing have made fragmented ones feel dated. “Neobanks recognised this early and built integrated services into their platforms from day one, raising the bar for the whole market,” he said.
The commercial consequence he draws is direct. Mainstream banks that fail to move beyond accounts and payments, he said, “risk losing Business Current Account market share, deposits and long term profitability”.
That is a claim with a number attached. Hartley said BankiFi’s own research suggests that of the 800,000 new business current accounts opened in 2025, fewer than 40 per cent were with mainstream banks. It is the company’s figure rather than an independent one, and it is doing a fair amount of work in the argument.
His prescription is partnership rather than in-house build. Banks should “focus on what they do best by providing trusted banking products such as accounts and payments, while specialist partners deliver the wider business workflows SMEs increasingly expect”, he said. Embedding invoicing, accounts payable, accounts receivable and bookkeeping into existing digital channels, on this reading, lets banks move faster without carrying the cost of building and maintaining every service themselves.
BankiFi’s collaboration with Lloyds Banking Group is the example he reaches for. It gives SMEs access to integrated invoicing, payments, bookkeeping, tax and cash visibility inside the bank’s digital channels, Hartley said, and its wider significance is what it says about sourcing. “It signals that even the UK’s largest banks recognise the value of partnering with specialist providers rather than building every capability internally.”
Asked where integrated workflows genuinely differentiate a business bank and where the claim is overstated, Hartley kept to the practical case. “The real differentiation comes from making everyday business tasks faster and simpler,” he said, and the point is not feature count. “The opportunity is not about adding more features. It is about creating connected experiences that become part of how businesses operate every day.”
He also accepts that the market has already moved. Customer satisfaction and advocacy, he said, have shifted towards neobanks alongside their growing share, “largely because they deliver stronger digital experiences”.
The obstacle he names is not the one banks usually cite. “The biggest challenge is cultural rather than technical or regulatory,” Hartley said, pointing to BankiFi’s partnerships with Lloyds Banking Group, The Co-operative Bank and Metro Bank as evidence the model works in practice. Success, he argues, “requires a shift from building everything internally to adopting a partnership led approach”.
That shift places a burden on the suppliers as well. Technology providers “must operate to bank grade standards, meeting the same expectations around security, resilience, governance and compliance”, he said.
Looking five years out, Hartley expects the integration to run in both directions: banks embedding third-party services in their own channels, and banking capabilities appearing inside the software businesses already use. The winners, he said, will be the banks “that embrace open ecosystems, build strong partnerships and position themselves at the centre of their customers’ financial lives”.
The losers, in his framing, are not banks that disappear but banks that shrink into a utility. Those that continue to focus solely on traditional banking products, he said, “risk becoming providers of accounts and payments while the primary customer relationship shifts elsewhere”.
Hartley has a commercial stake in that outcome. BankiFi sells the embedded workflows he is arguing banks should buy rather than build, and the Lloyds, Co-operative Bank and Metro Bank relationships he cites are its own. The next test of the thesis is whether business current account share among mainstream banks recovers as those partnerships reach customers.
The post BankiFi’s Hartley on Banks Becoming the SME Gateway appeared first on The Fintech Times.