After CLARITY: Building Through the Next Phase of Crypto Rulemaking
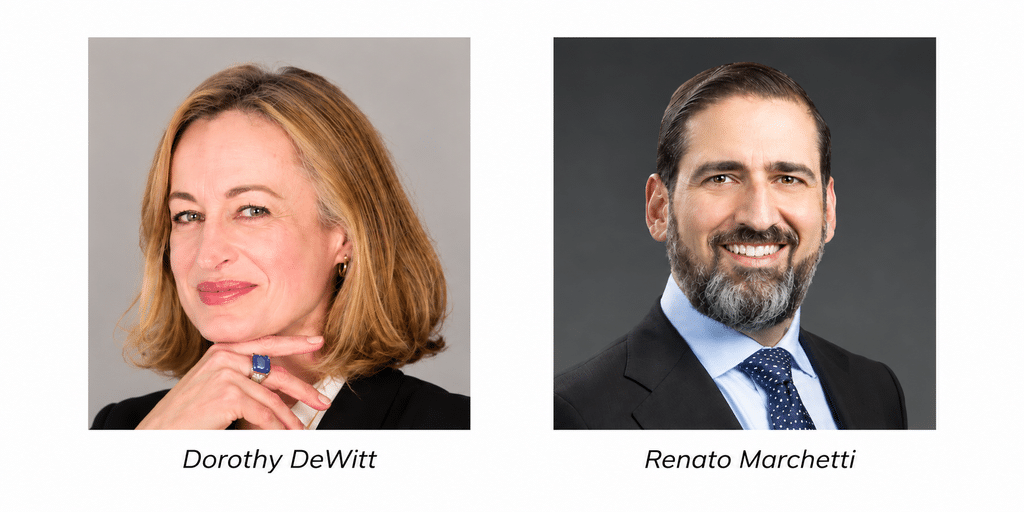
By Dorothy DeWitt, founder and CEO of Tölt Strategies and Renato Mariotti, partner at Paul Hastings
The Senate’s failure to advance the CLARITY Act has put a major congressional effort to establish a comprehensive U.S. digital asset market structure framework on hold. On September 15, the Senate voted 49-50 against invoking cloture on the motion to proceed, leaving the legislation stalled for the time being.
That does not mean the regulatory agenda has stopped. The Securities and Exchange Commission (SEC) and Commodity Futures Trading Commission (CFTC) were already moving on digital asset regulation before the vote. On October 5, the CFTC issued its Advance Notice of Proposed Rulemaking (ANPRM) titled “Regulation Crypto Asset Transactions and Regulation Crypto Asset Markets.” Comments are due December 14.
What changes when the immediate path shifts from legislation to agency action? And how should firms build when the direction of regulation may be getting clearer, even as the legal framework remains unsettled?
Dorothy DeWitt and Renato Mariotti discuss what comes next and what digital asset market participants should be thinking about now. DeWitt is founder and CEO of Tölt Strategies, former Director of the CFTC’s Division of Market Oversight and former General Counsel of Coinbase. Mariotti is a partner at Paul Hastings.
The following conversation has been edited for length and clarity.
At a high level, what changes now that the CLARITY Act has stalled?
Renato Mariotti: I think it changes the instrument through which change is going to occur more than it changes the direction. The commissions were already moving. The immediate implication is that they now have to carry much more of the load. At this point, I don’t think firms should be building their business plans around the assumption that Congress is going to solve this anytime soon. They need to be watching what the SEC and CFTC are actually putting forward and planning around that. The CFTC’s new advance notice under Chairman Selig gives the industry its first concrete look at a federal crypto exchange subcategory, the Crypto Asset Market, or CAM. It is not a proposed rule yet. The next step is a formal proposal, and I don’t expect a final rule before late 2027.
Dorothy DeWitt: I agree with that. But there’s also an important difference between an agency implementing a new law and an agency trying to make use of the authority it already has. If CLARITY had passed, the CFTC and SEC would have had a new statutory framework to implement. Without it, they still have to tie whatever they do back to the current Commodity Exchange Act (CEA) and the federal securities laws. So the agencies can provide more rules of the road, but they can’t simply create new and expanded jurisdiction that CLARITY would have done legislatively. The advance notice cleverly re-interprets certain provisions of the CEA.
How far can the CFTC go under its existing authority?
DeWitt: There is historical precedent for trying to regulate around a gap. Retail foreign exchange is a good example. In the late 1990s and early 2000s, those markets grew very quickly, and there were significant problems with fraud and manipulation. The CFTC tried to assert jurisdiction over parts of that activity, but courts pushed back where the transactions looked like spot products rather than futures, options or swaps. What developed after that was more of an entity-based approach. The National Futures Association (NFA) imposed requirements on its members who transacted in those spot markets, even where the CFTC’s and NFA’s jurisdiction over the underlying spot products was less straightforward. Only the firms opting into NFA membership followed those requirements.
What does the CFTC’s advance notice actually do?
DeWitt: Now, under the new proposal, the CFTC is aggressively re-interpreting Section 2(c)(2)(D) of the CEA—originally a fix for foreign exchange fraud. That section provides that an exchange that offers or transacts in any commodity involving retail participants on a leveraged, margined or financed basis must treat those transactions as if they were futures, unless the exchange satisfies the “actual delivery” exception by actually delivering the commodity to the buyer within 28 days of the transaction. That has historically meant that the exchange must register with the CFTC as a Designated Contract Market (DCM) to offer leverage, unless it meets the actual delivery requirement on all transactions. The advance notice suggests that a spot crypto exchange that offers leveraged, margined or financed transactions, even if none is entered into, to retail market participants without satisfying the actual delivery requirement must register as a DCM or the new CAM registration subcategory. The CFTC’s preliminary view is that actual delivery means the customer gets real possession and control, such as moving the token to the customer’s own non-custodial wallet. The notice refers to these transactions as Crypto Asset Transactions, or “CTXs.”
One might ask if the CFTC can create a new registration category, here a CAM, out of whole cloth. The CEA – not the agency – defines the registration categories. But also cleverly, the rule proposal provides that a CAM registration is a subcategory of the existing DCM registration. There is precedent for subcategories of registrations created by rulemaking, including Section 4(c) Commodity Pool Operators, which operate with lighter standards than full CPOs. But to the extent an agency is creating a new registration (sub)category, one can wonder about the proposed rule’s consistency with the USSC’s 2024 decision in Loper Bright, eliminating Chevron deference to agencies in matters of statutory interpretation under the Administrative Procedures Act.
Mariotti: The forex history is useful because it shows both sides of this. There are things the regulator can potentially do through registrants, membership requirements and interpretations of its existing statute. But it also shows you what happens when the statutory authority doesn’t quite match what the regulator is trying to accomplish. Eventually, Congress had to step in. And I think we see a version of that tension again here. The advance notice also contemplates routing customer-facing CTX trading through futures commission merchants—the brokers that hold customer accounts in futures markets. That’s an ambitious use of existing authority, and I expect it to draw a lot of comment.
DeWitt: One thing I would add is that the question goes beyond whether you can create requirements. Whether you can actually examine the firms subject to them also matters. Spot crypto exchanges that don’t offer CTXs can opt-in to CFTC regulation by offering them. Spot crypto exchanges that prefer not to offer CTX’s will remain regulated by the states.
Mariotti: I think that gets to one of the big questions in the CFTC’s advance notice. CFTC leadership has already taken the position that the CEA permits leveraged spot crypto on a CFTC-registered exchange. But non-leveraged spot is much harder. The advance notice answers that by using leverage as the hook. A platform that never offers leverage can stay with state regulators, though the CFTC’s anti-fraud and anti-manipulation authority still reaches it. The legal question I’d watch is the other side of that line. Once a platform offers leverage, the CFTC’s preliminary view is that the offer can bring its other trades into the framework, even those no customer bought on margin. Whether the statute stretches that far is where I’d expect the first fight.
Registration also cuts both ways. A CAM would be a type of DCM, so the federal anti-spoofing law and the exchange’s own surveillance would apply to everyone trading there.
For firms watching this process, is the message to start building now or wait for more certainty?
Mariotti: I would stop waiting for a congressional solution. But that doesn’t mean I would launch a business tomorrow based purely on a proposed rule. If the proposal affects your business model, participate in the process. Comment. Comments on the CFTC’s advance notice are due December 14. Engage with the Commission. Understand what legal interpretation or relief you’re relying on. Time to market matters, but there can be meaningful changes between a proposal and a final rule.
DeWitt: Exactly right. The notice-and-comment process is going to tell us a lot. Market participants will look at the ANPRM and identify where they think the Commission is on firm ground and where it may be more vulnerable, and what changes are in order. The CFTC then has to address those comments when it moves toward a proposed rule and then a final rule. So firms can start planning, but they need to preserve flexibility.
Are there areas where firms can move ahead with more confidence?
DeWitt: It’s a difficult question to answer, but in general, yes. I would start with systems and controls that support transparency, market integrity and customer protection that underlie the Core Principles for DCMs provided by the CFTC. As former Division of Market Oversight Director, I am familiar with how to innovate under core principles, which are fortunately flexible, and the ins and outs of the process of filing comment letters and rulemaking. Renato and I have advised clients for years on how to implement the core principles. Some specific requirements may change, but you are unlikely to regret building strong controls around those basic objectives. Luckily for the industry, the proposed CAM Core Principles are closely mapped to traditional DCM Core Principles, so areas that will likely carry over to the next administration include Bank Secrecy Act / Anti-Money Laundering (BSA/AML) programs, Office of Foreign Assets Control (OFAC) sanctions screening, trade practice surveillance, customer asset segregation for intermediaries, system safeguards and conflicts of interest.
Mariotti: I agree with Dorothy on that. But even then, it’s hard to draw a circle around a product or business model and say, “This is safe. Go ahead.” Things like strong controls, good governance and documenting the basis for your compliance decisions are useful regardless of where the final line gets drawn. But firms should still be ready to engage with the process and stay adaptable. And practically, I would also be checking your state licensing position. The absence of CLARITY means you don’t have the broad federal preemption that legislation could have provided. The SEC’s token-offering proposal would preempt some state securities registration requirements, but it’s still a proposal, and it doesn’t touch state money transmitter licensing.
Does that also mean the post-CLARITY picture is broader than just the SEC and CFTC?
Mariotti: Absolutely. That’s part of what makes this more complicated than simply shifting the conversation from Congress to the SEC and CFTC. There are issues CLARITY addressed that those commissions can’t simply resolve themselves. Software developers and money transmitter laws bring Treasury and DOJ into the picture. Stablecoins can implicate other regulators. Decentralized protocols still have open questions. And protecting customers’ crypto if an exchange fails would take changes to the Bankruptcy Code that only Congress can make.
DeWitt: And the same is true at the state level. Unless federal law clearly preempts state authority, state regulators may be able to continue to regulate, imposing their own requirements. We’ve seen some of those dynamics play out around prediction markets. There’s no reason to assume financial regulators at the state level won’t look at similar approaches elsewhere in crypto. The ANPRM posits that the current patchwork of state money transmitter laws is inadequate for financial market risks. The CFTC’s preliminary view is that federal regulation of CTXs would preempt conflicting state laws, potentially including some state money transmission requirements. How far that reaches is uncertain. Under current regulations, FCMs perform Know Your Customer (KYC) and AML functions. The good news is that exchanges listing futures enjoy preemption; only time (and possibly the courts) will tell if preemption exists for those exchanges insofar as they also list their non-leveraged spot transactions.
Mariotti: That’s why I’m a little more measured than some of the excitement I’m hearing from the industry right now. People are eager to build, and I understand why. But a welcoming environment today doesn’t mean the risk disappears two or four years from now.
So what does a durable strategy look like in an environment that could continue to change?
DeWitt: Again, I would focus first on the things that tend to survive changes in administrations: customer protection, market integrity, transparency, strong governance and sound risk management. There’s plenty of precedent for industries developing durable standards before the law fully catches up. Insurers in New York, for example, helped develop fire-safety standards by deciding what they would and would not insure. Over time, those practices became broadly accepted and were adopted into law. That doesn’t mean industry should replace regulation, obviously. But regulators, advisors, market participants and other gatekeepers can help establish practices that make sense regardless of exactly where the statutory lines and policymakers end up.
Mariotti: That’s a great point. And to me, that’s why the CFTC side of this is particularly interesting right now. There is going to be plenty written about the SEC. But for firms that were expecting broader CFTC spot-market authority under CLARITY, the next few months could force some very practical decisions. That doesn’t mean firms can’t move forward. The important thing is understanding which parts of that path rest on clear statutory authority as opposed to agency interpretation, and where the legal and regulatory risk still remains.