Data Centers Are Funding the Energy Technology All Buildings Will Benefit From
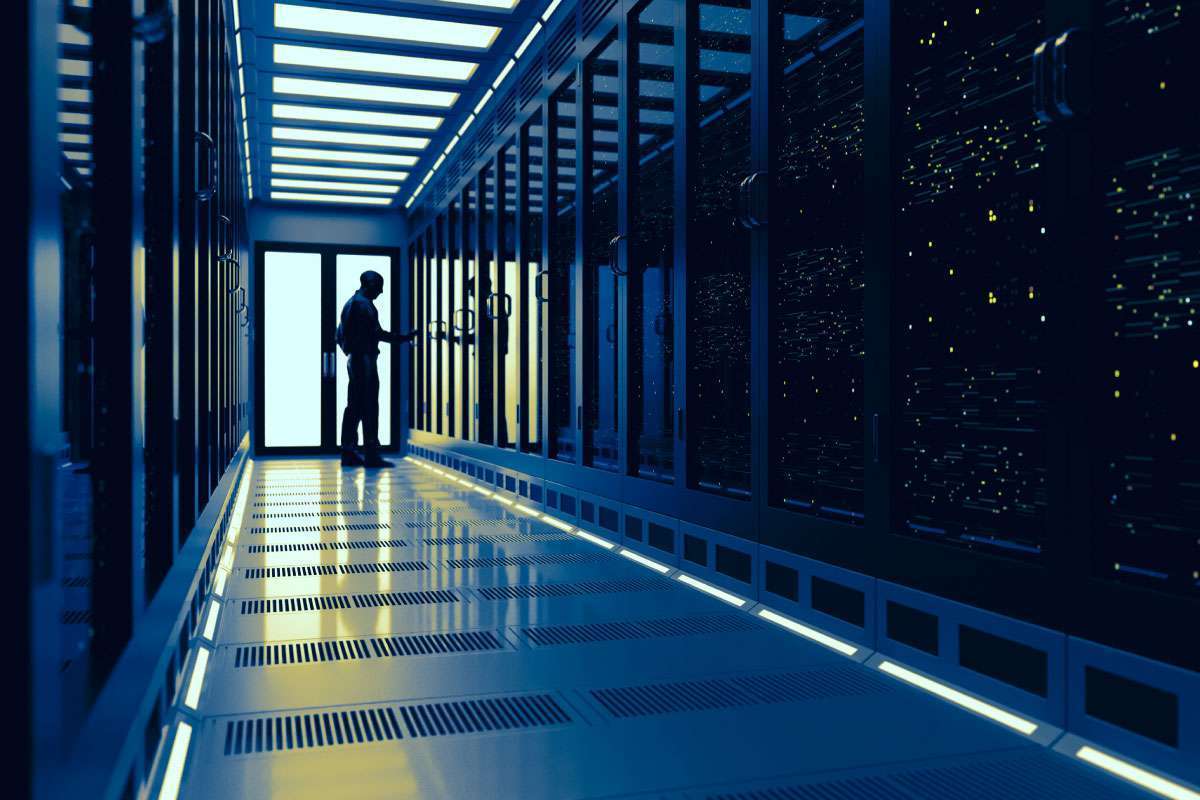
The energy technology that commercial buildings have been circling for years, on-site storage, microgrid controls, islanding capability, is getting cheaper and more capable at a pace nobody in real estate paid for. Data centers are driving it. Facing grid constraints severe enough to stall multi-billion dollar projects, the AI buildout has poured capital into solving energy problems that building owners share but could never have funded on their own. The solutions are portable, and they are arriving in the commercial market as a byproduct.
US data center electricity demand climbed from roughly 23 gigawatts in 2023 to about 42 in 2026, and the forecasts for where it goes next are large enough that the range between them exceeds what most sectors consume in total. Deloitte projects 176 gigawatts by 2035. Goldman Sachs expects US data center power demand to more than double between 2025 and 2027. McKinsey attributes roughly three quarters of all US power demand growth through 2030 to the sector.
The grid was not built for that, and it cannot be rebuilt quickly. Around 2 terawatts of generation and storage capacity sits in US interconnection queues, close to twice the currently installed fleet, with a median wait from request to commercial operation now exceeding five years. Northern Virginia connections can take more than seven years. Texas has 86 gigawatts of pending interconnection requests through 2031, roughly equal to the state’s entire existing grid capacity.
Faced with waits that long, data center developers stopped treating grid power as the only option. On-site generation, large-scale battery deployments, and behind-the-meter microgrids moved from contingency planning into primary strategy, backed by capital at a scale the energy technology sector had never seen from a single customer segment. The industry had to become an energy player because the alternative was not building.
Commercial energy storage has needed volume to bring costs down for a decade, and data centers are supplying it. The microgrid battery storage market is projected to grow from $8.4 billion in 2026 to $39 billion by 2035, with manufacturing capacity and cost curves responding to demand that originates almost entirely outside commercial real estate. A property owner evaluating storage in 2027 will price hardware that got cheaper because hyperscalers needed it first.
The same dynamic is working through the controls layer. Managing a facility that generates its own power, stores it, and decides moment to moment whether to draw from the grid requires software that did not exist in mature form a few years ago. Data center operators funded that development because their uptime requirements left no room for it to work poorly. Islanding capability, the ability to disconnect from utility lines and run independently while keeping local loads served, now ships in commercial hybrid inverters as a standard feature rather than a custom engineering project.
Utilities are adapting in ways that extend the benefit further. Several have introduced expedited permitting and interconnection pathways for projects that can demonstrate flexible load or on-site generation, since a customer able to reduce consumption during peak events is easier to serve than one who cannot. Incentive programs for demand response and behind-the-meter storage have expanded in the markets where capacity is tightest, reflecting a calculation that paying existing customers to shift load costs less than building new transmission.
For commercial buildings, energy investments are an easier sell. Demand charges, which bill based on a customer’s highest consumption, get more expensive as grid capacity tightens. On-site storage addresses that directly. The same equipment qualifies for utility incentive payments and can earn revenue through demand response participation.
Buildings able to island are also worth more to the grid than they used to be. A property that can separate itself during a stress event removes demand from a constrained system at the moment that demand is most expensive to serve. Aggregated across enough sites, that capability starts to function as dispatchable capacity, and virtual power plant programs are beginning to treat commercial buildings accordingly. Commercial real estate has been described as the largest untapped distributed energy resource available to address US grid shortages, and the technology to access it is arriving on someone else’s development budget.
Constraints remain. Battery supply chains are tight, transformers are quoted in years rather than months, and several states have begun imposing review requirements on large loads that may slow the data center buildout driving all of this. Texas passed SB 6 last year, adding a six-month review for projects above 75 megawatts along with new interconnection costs and curtailment requirements.
We are likely to see the gap between what a sophisticated data center can do with energy and what a well-run commercial building can do continue to narrow. The same cutting-edge techniques being developed at data centers will eventually become commonplace. Love or hate data centers they have to get credit for pushing utilities and industry to move faster when it comes to adopting much needed energy technology.
The post Data Centers Are Funding the Energy Technology All Buildings Will Benefit From appeared first on Propmodo.