DERIVSOURCE: Perpetuals and Prediction Markets Raise New Questions for Derivatives Market Structure
Traditional exchanges and blockchain-based trading platforms are taking different approaches to perpetual futures and prediction markets, with differences in clearing arrangements, liquidity provision and risk controls shaping how these products are brought to market.
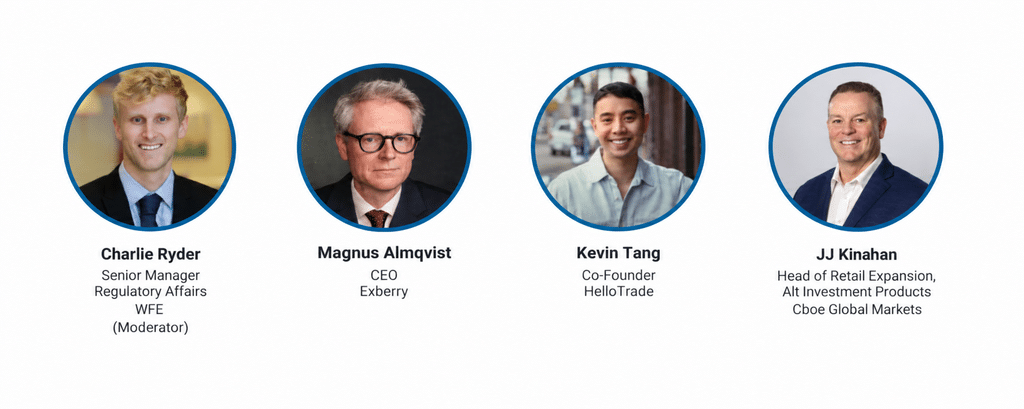
During a recent World Federation of Exchanges (WFE) webinar, Perpetuals and Prediction Markets: The New Derivatives Landscape, JJ Kinahan, Head of Retail Expansion, Alt Investment Products at Cboe Global Markets; Kevin Tang, Co-Founder of HelloTrade; and Magnus Almqvist, CEO of Exberry, discussed the operational requirements of these products, regulatory uncertainty and institutional participation. The discussion was moderated by Charlie Ryder, Senior Manager, Regulatory Affairs at WFE.
Tang attributed the growth of perpetual futures in cryptocurrency markets to their capital efficiency, simplicity and suitability for continuous trading. Unlike traditional futures, perpetual contracts have no fixed expiration date and use a funding mechanism to help keep prices aligned with the underlying asset. “The first one is perps are highly capital efficient,” Tang said, adding that their relative simplicity compared with traditional futures and options has also contributed to adoption.
However, Kinahan cautioned that funding payments could prove difficult for retail traders to understand, particularly when positions are held for longer periods. “You can actually be right,” he said, describing a situation in which an investor correctly anticipates a price increase but must still make a funding payment. Kinahan said the funding mechanism would require further investor education, particularly in the United States.
Turning to prediction markets, Kinahan discussed Cboe’s plans for contracts tied to corporate key performance indicators (KPIs), allowing investors to express views on specific financial outcomes rather than predicting the direction of a stock. He argued that investors can correctly anticipate strong corporate results but still lose money if the stock reacts negatively to earnings guidance or other factors. “What KPIs allow you to do is to really dig down and have an investment opinion on the areas of a company you’re actually observing,” he said.
Kinahan emphasized that Cboe is concentrating on financially relevant events rather than sports or entertainment contracts. “We are not doing sports, we are not doing culture. We’re doing things we feel are truly influencing the market,” he said.
He compared the potential adoption of KPI contracts to the development of zero-days-to-expiration (0DTE) options, where retail demand attracted market makers and subsequently institutional participation.
Kinahan described how Cboe’s plans for company KPI contracts have required changes to its clearing arrangements. While the exchange traditionally clears options through the Options Clearing Corporation (OCC), Kinahan said the clearinghouse’s ongoing technology modernization meant it could not immediately accommodate the proposed products.
Cboe has consequently been seeking regulatory approval to clear the contracts through its own clearing infrastructure, he said. Kinahan added the company had received regulatory permission for the product and was awaiting approval related to its clearing arrangements at the time of the webinar.
For blockchain-based platforms, Tang identified liquidity provision as a challenge when launching perpetual futures markets. “To bootstrap these markets, this requires capital, requires market makers, requires both taker and maker liquidity, and this can be challenging, especially for new platforms,” he said.
Tang argued that blockchain technology could facilitate capital formation through trading incentives, permissionless participation and liquidity arrangements. He also pointed to demand from investors in emerging and frontier markets who may have limited access to traditional brokerage platforms.
Infrastructure for Continuous Trading
Almqvist said regulatory uncertainty remains a common challenge across jurisdictions, alongside settlement arrangements, risk management and the operational implications of longer trading hours. According to Almqvist, moving toward continuous trading affects exchange operations, including IT systems, collateral transfers, settlement and internal risk management. “The rate of the change in the markets today is the fastest I’ve ever seen through my career,” he said.
Almqvist emphasized that infrastructure must accommodate new instruments, handle increases in trading volumes and allow exchanges to introduce upgrades without disrupting operations. He also highlighted the need for closer integration between trading, risk management and settlement systems. “You need a settlement and risk function that sits very, very closely with your matching engine,” he said.
Almqvist explained that this differs from traditional architectures in which matching engines, collateral management and clearing systems have often operated as separate components. He also highlighted the importance of infrastructure capable of handling sudden increases in trading activity, particularly in event-driven markets where volumes can be concentrated around specific outcomes.
Tang identified risk management as a priority, particularly for perpetual futures linked to traditional assets that lack reliable price feeds outside normal market hours. He said operators need to incorporate safeguards used in traditional markets, including price bands, open interest limits and circuit breakers.
Kinahan similarly emphasized the importance of maintaining market confidence. “If somebody has bad risk management, it actually reflects on the whole industry,” he said.
Tang said hedge funds and institutional market makers are already participating in cryptocurrency derivatives markets, although technological integration, compliance requirements and smart contract risks remain obstacles for institutions considering on-chain trading. “The biggest blocker right now that I see, especially with on-chain venues, is that there is smart contract risk,” he said.
Tang also noted that traditional portfolio managers are monitoring perpetual futures prices over weekends for indications of how underlying markets may open when regular trading resumes.
Looking ahead, Kinahan expects closer integration between traditional derivatives markets and blockchain-based trading platforms, particularly as exchanges explore extended trading hours and changes to clearing infrastructure. “You’re seeing a lot more merging of ideas and a lot more merging of firms willing to say, you know what, maybe both sides know a little something,” he said.
Tang also expects further convergence between traditional and decentralized markets, supported by regulatory developments and greater institutional participation. However, he does not expect perpetual futures and prediction markets to replace established derivatives products. “I don’t believe that we will see the end of options and traditional futures,” Tang said.