Car owners delay repairs amid affordability challenges
If you have been shopping for one in 2026, then you don’t need me to tell you how unaffordable new car purchases have become.
The average transaction price for a new vehicle in the U.S. increased for the fourth consecutive month in September to $50,562, according to Kelley Blue Book, placing it just below the all-time record of $50,514 that was set in December last year.
Also read: Why your next car purchase will be an affordability nightmare
As a result, many car owners are just holding on to their old vehicles. But now even that is becoming financially unsustainable, as the cost of repairs, parts, and services has also jumped, according to a recent Bank of America note shared with TheStreet.
Analysts surveyed 70 dealerships last month on issues related to retail, inventory, and service trends. They also conducted a pricing study to find out which services are being discounted.
Here’s what they found.
Car parts and services are becoming unaffordable
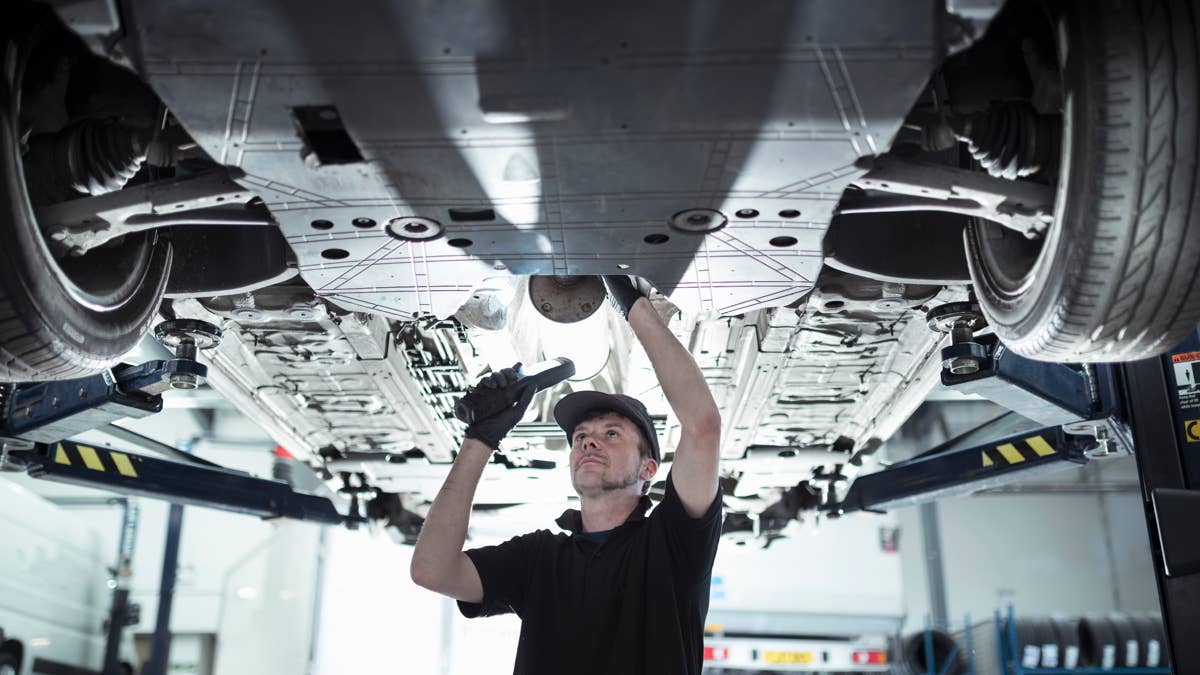
Car repairs are a tricky situation. Everyone knows that ignoring that knock in your engine only makes it get worse over time, so most people can’t afford to put off repairs, even if they can’t afford it.
Service traffic at auto dealers held up for the most part in September, with 51% of BofA survey respondents reporting higher repair orders year over year, versus 24% reporting declines.
However, 56% of the dealers they surveyed reported seeing some pushback on pricing as customers defer work, while another 11% reported losing repair orders.
This situation has created a bit of a bright spot for consumers, however, as dealers offer discounts in order to get more customers through the door.
Here’s where to find those discounts.
For oil changes, go to the dealer; for brakes, go independent
Car owners have two options when it comes to vehicle repairs. They can go back to the dealer or go to an independent shop.
Both options have their pros and cons, especially in a market that is getting highly competitive, thanks to consumer reluctance driven by high prices.
For oil changes, dealers are pricing their services about 32.4% lower than independent shops, according to BofA, likely to attract customers. However, they are also pricing brake jobs 17.5% higher (or $95 more) per job than their independent competition.
Four out of five public dealer groups were pricier on brakes, with GPI, which produces parts for Chevy, Ford, Honda, Mazda, Mitsubishi, and Toyota, being the lone outlier, “consistently pricing below independents,” according to BofA.
The reason for the discrepancy in price is labor, according to the firm.
“While dealers’ use of higher-priced original equipment manufacturer parts explains some of that gap, labor rates are a cleaner comparison: dealer labor averaged $253/hour vs. $216 at independents,” the note said.
Interest rates are also hampering auto loan affordability
The United States Federal Reserve has been hawkish this year, raising its benchmark interest rate by a quarter point in September to a target range of 3.75% to 4%. It was the central bank’s first rate hike in more than three years.
As the federal government raises the cost of borrowing, the rest of the financial sector follows suit, including the banks financing auto loans.
“Borrowing cost relief has also stalled, with a potential increase ahead following the sharp move higher in Treasury yields. As our U.S. Economists highlighted, declines in auto loan rates from mid-2024 through early 2026 have leveled off as financial conditions tightened, while mortgage rates have already reaccelerated,” Morgan Stanley analyst Andrew Percoco wrote in a recent note.
According to Morgan Stanley, nearly 85% of existing U.S. household debt is fixed-rate, which means most of it is insulated from the recent changes to interest rates.
But consumers looking to finance the purchase of a new vehicle would be taking on new debt.
“Consumers taking on new debt, however, remain directly exposed to tighter financial conditions, particularly for large-ticket purchases such as autos,” Percoco said.
“Wealth provides an additional cushion for higher-income households, while lower- and middle-income consumers have less balance-sheet support. This helps explain why broader consumer spending can remain resilient even as affordability deteriorates.”
Related: Why your next car purchase will be an affordability nightmare