Furaha Reaches 100,000 Ugandan Children with School-Fee Credit
Furaha Financial, an education lending fintech incubated by SC Ventures and headquartered in Kampala, says it has helped parents finance school fees for 100,000 Ugandan children since launching in 2024. The company is now setting its sights on 10 million children across Africa by 2030, positioning the Uganda milestone as a proof of concept for a broader continental rollout.

The model is built around a structural mismatch in African household finance: school-fee payment deadlines rarely align with the irregular income cycles of informal workers, and millions of parents lack the payslips, collateral or formal credit histories that commercial banks conventionally require. Furaha sits between these parents and its banking partners, namely Diamond Trust Bank Uganda, Cairo Bank Uganda, Opportunity Bank and FINCA Uganda, providing the technology layer for customer onboarding, KYC, alternative-data credit scoring, loan disbursement and collections.
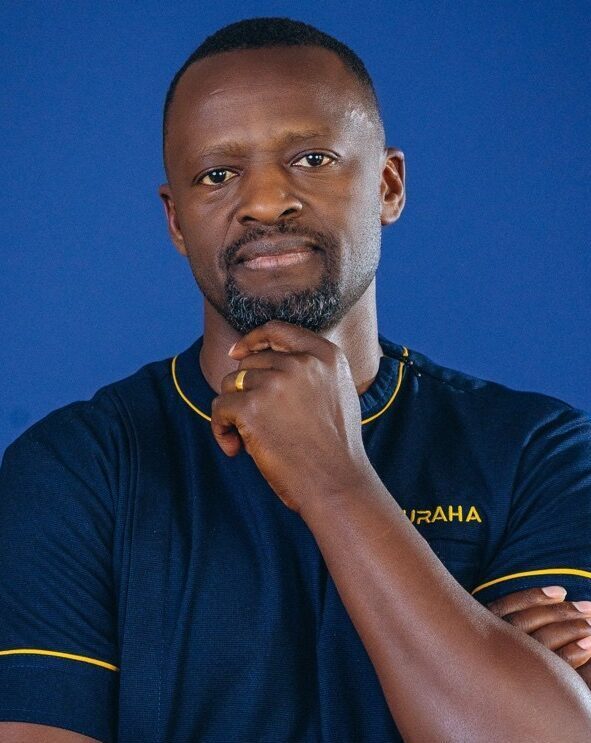
“Millions of parents have never been seen by traditional credit systems, not necessarily because they can’t repay, but because the data needed to assess them has not existed in one place,” said Yustus Aribariho, co-founder of Furaha. “By bringing together mobile-money, school-payment and other alternative data, we can give financial institutions a broader view of customers.”
The ecosystem model

Furaha’s approach is deliberately multi-sided. Beyond its bank partners, the platform connects mobile-money operators MTN and Airtel with school-fee payment platforms SchoolPay, SurePay and PegPay. Co-founder Ian Fernandes described the rationale as recognising that no single institution could independently solve the problem each term, and that Furaha’s role is to act as the connective layer across the ecosystem.
Chief executive Dennis Musinguzi described the 100,000 figure as a proof point rather than a destination, and said the next phase involves taking the model to more families and more African countries. The company has not yet disclosed which markets it intends to enter next, nor detailed the funding position that will support that expansion.
Market context and regulatory landscape
The education-finance segment remains largely untapped by formal lenders across sub-Saharan Africa, where UNESCO estimates that the region accounts for nearly 40 per cent of the world’s out-of-school children. UNESCO’s 2026 Global Education Monitoring Report notes that enrolment across the region has expanded, yet the absolute number of out-of-school children continues to rise, partly because financing is only one of several barriers to attendance.
Furaha’s claim to be the first lending fintech in Africa to channel affordable commercial-bank financing specifically toward education needs is notable but not independently verified. The broader alternative-data credit scoring space is active across East and West Africa, with several fintechs, including M-Kopa, Tala and branch-network lenders, using mobile and transaction data to extend consumer credit. What distinguishes Furaha is the specific school-fee use case and the direct integration with fee-payment platforms, which creates a closed-loop data environment that may improve repayment predictability.
From a regulatory standpoint, Furaha operates as a technology platform rather than a licensed lender itself, meaning credit risk sits with its partner banks. This structure is common in embedded-finance and banking-as-a-service arrangements globally and allows faster scaling without the capital and prudential requirements of a full banking licence. However, it places Furaha in a similar position to the bank-fintech middle-layer models that have attracted regulatory scrutiny in more developed markets: the platform’s operational resilience and data-governance practices become critical to its banking partners’ own compliance posture.
The next milestones to watch are geographic expansion announcements, any disclosed funding round to support the 2030 ambition, and whether Furaha extends its bank partnership roster beyond Uganda.
The post Furaha Reaches 100,000 Ugandan Children with School-Fee Credit appeared first on The Fintech Times.