Costco shoppers are changing in a way the retailer cannot ignore
Costco gave investors plenty to like in its latest fourth-quarter 2026 earnings report.
Sales climbed by double digits, profit beat expectations, and margins improved.
But beneath the strong quarter, one issue kept resurfacing in Wall Street’s reaction to the results.
Costco’s membership base is still growing, but the pace of that growth is slowing.
And why is it important?
Because Costco membership is central to the retailer’s business model.
And it has helped investors justify paying a significant premium for the stock.
I discussed it in my previous earnings preview, noting that Bank of America lowered its Costco price target to $1,095 from $1,200 while maintaining a Buy rating.
After the results, BofA did not back away from its overall bullish view.
Instead, analyst Christopher Nardone described the quarter as “steady as she goes” in a note shared with TheStreet.
He maintained the firm’s $1,095 price objective and slightly increased its fiscal 2027 earnings estimate.
But the report also highlighted the same membership trend that several other analysts are also watching closely.
Costco’s customer base is changing in two important ways.
Membership growth has slowed for eight consecutive quarters, while younger shoppers are becoming a much bigger part of the warehouse chain’s business.
Costco earnings beat expectations
Costco reported fourth-quarter net sales of $93.87 billion, an 11.2% increase from a year earlier.
Net income rose to $2.998 billion, or $6.75 per diluted share, compared with $2.61 billion, or $5.87 per share, a year ago.
More Retail:
- Dollar General CEO raises major red flag about consumers
- 44-year-old mall retailer shut 40 stores, now it’s turning a profit
- DSW has a surprising new plan to get shoppers to spend
Comparable sales increased 9.4% across the company. Digitally enabled comparable sales jumped 19.5%.
Shoppers also continued to visit Costco more frequently and spend more when they did.
Personally, I am more of a get-it-delivered person, and it helps that Costco now offers that option across Instacart, Uber Eats, and DoorDash.
Shopping frequency increased 3.3% worldwide during the quarter, while the average transaction increased 5.9%.
The bank also found that Costco’s underlying margins improved by 18 basis points after excluding the tariff refunds.
Supply-chain efficiencies, labor productivity in fresh foods, and a stronger sales mix in non-food merchandise helped improve margins.
BofA slightly increased its fiscal 2027 EPS estimate to $22.83 from $22.79 and maintained its $1,095 price target.
So the issue after earnings is not that Costco’s underlying business suddenly looks weak.
Quite the opposite.
The debate is increasingly about how much growth investors should expect from a company whose stock already trades at a premium to much of the retail sector.
Costco membership growth slows
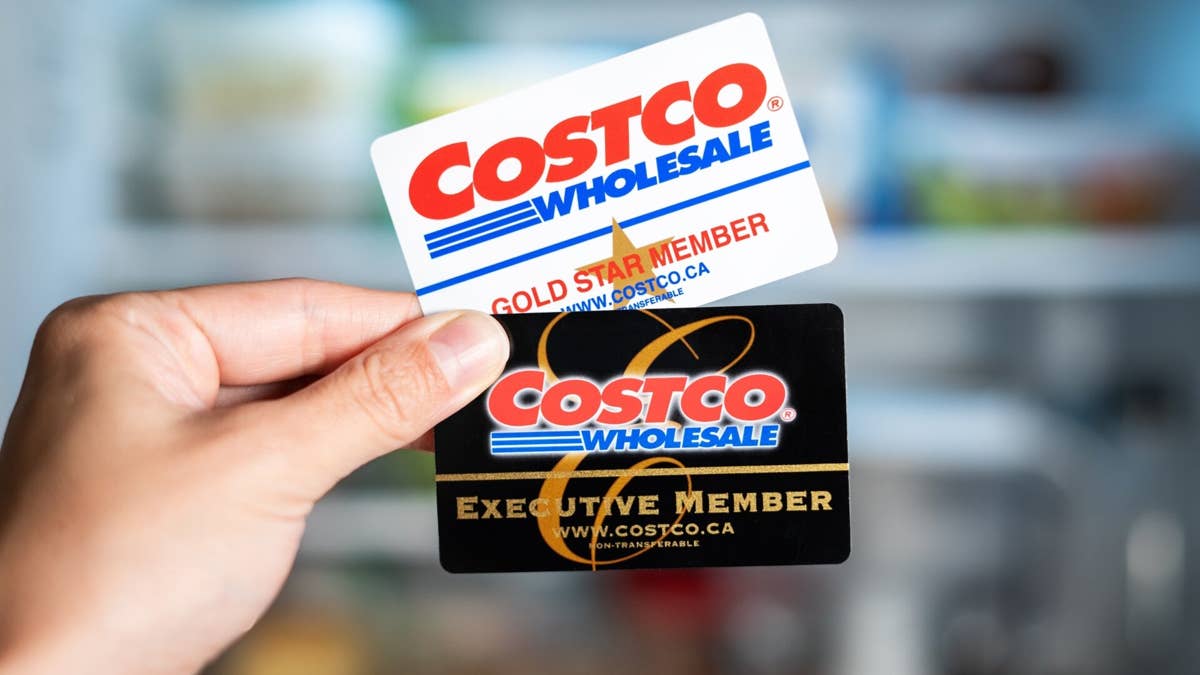
Costco ended the quarter with 84.1 million paid members, up 3.8% from a year earlier, while paid Executive Memberships reached 42.3 million.
Costco’s worldwide membership renewal rate improved by 10 basis points sequentially to 89.8%, while the U.S. and Canada renewal rate increased to 92.3%.
These numbers show that existing members continue to stick with the retailer.
But total paid membership growth slowed to 3.8% from 4.1% in the previous quarter, while Executive Membership growth also moderated.
And the slowdown is not limited to one quarter.
During Costco’s earnings call, Truist analyst Scot Ciccarelli noted that membership growth has now slowed for eight consecutive quarters.
Costco CFO Gary Millerchip described the trend as a “normalization” after strong growth driven by younger, more digitally engaged members.
He also suggested the recent pace may not reverse immediately, saying the growth rate seen in recent quarters is “probably more typical of what we’d expect to see.”
Costco is nevertheless attracting a different generation of customers.
The retailer said its membership base under age 40 has grown nearly 60% since the COVID pandemic, and those shoppers now make up more than one-quarter of its members.
Younger customers initially spend somewhat less, Costco said, but tend to become higher-spending members over time.
That distinction helps explain why management is focusing not only on how quickly its membership count grows, but also on how much existing members shop.
Costco said Executive Membership penetration, gas engagement, and digital engagement all reached record levels during fiscal 2026.
Analysts remain divided on Costco’s valuation
The slowdown in headline membership growth has fueled much of the debate around an otherwise strong quarter.
Several firms lowered price targets for Costco, citing membership trends and valuation as key concerns.
Truist lowered its Costco price target to $955 from $1,011 and maintained a Hold rating.
The firm said membership growth has continued to slow, although part of that reflects where Costco has been opening warehouses.
More of Costco’s recent locations have been “fill-in” warehouses in existing markets, rather than openings in places such as Asia, where a new location can generate a large wave of new member signups.
Truist said Costco’s business remains “incredibly strong,” but membership growth may need to accelerate again before investors are willing to pay a higher valuation multiple for the stock.
JPMorgan made a similar distinction.
The firm lowered its Costco price target to $1,015 from $1,100 while maintaining an Overweight rating.
The bank noted that membership growth could give bears something to point to, particularly given Costco’s valuation.
At the same time, JPMorgan continues to view Costco as one of the retail industry’s most consistent market-share gainers, with a highly visible long-term warehouse expansion story.
DA Davidson, however, moved in the other direction.
The firm raised its price target to $1,040 from $1,000 and maintained a Neutral rating, describing the fourth quarter as another in a long string of strong earnings reports.
Few are questioning the health of Costco’s business.
They are debating what that strength is worth.
BofA argues that Costco deserves a premium because of its comparable-sales performance, high renewal rates, strong store execution, and international growth opportunities.
Costco plans to open new warehouses
Costco may have an answer to its slower membership growth: open more warehouses, particularly in new markets.
Costco ended fiscal 2026 with 939 warehouses worldwide.
The company plans to open 33 warehouses during fiscal 2027, including five relocations, resulting in 28 net new locations.
This compares with 25 net new warehouses in fiscal 2026.
Management is working to eventually open around 30 net new warehouses per year.
New markets can generate large numbers of memberships, while fill-in locations typically attract fewer new signups but mature more quickly in terms of sales and profitability, Costco CEO Ron Vachris said during the company’s earnings call.
Costco also noted that fiscal 2026 did not include any major new warehouse openings in Asia that would normally drive a membership spike.
This could change as its international pipeline expands.
Four of the planned fiscal 2027 openings are in Europe, five are in Canada, and one is in Mexico.
Costco also expects a stronger pipeline of openings in Asia and Australia in fiscal 2028, which Millerchip said could become a catalyst for faster headline membership growth.
If Costco’s track record in Japan is any indication, its upcoming expansion across Asia could provide the membership spike Wall Street is looking for.
All this as the company continues to find ways to increase store visits in international locations.
Tariff refunds give Costco room to cut prices
Costco also received an unexpected boost during the fourth quarter.
The company received $184 million in tariff refunds, representing a little more than one-third of the refunds it expects to ultimately receive.
But instead of using all of it for profit, Costco reinvested roughly half of the gross proceeds into lower prices for members, according to BofA.
You can read more of my coverage on how big-name retailers like Walmart and others are using these tariff refunds here.
And the refunds haven’t stopped.
Costco said it has already received about another $184 million in tariff refunds since the start of fiscal 2027, roughly matching what it received in the fourth quarter.
“We intend to continue reinvesting the majority of the dollars we receive in increased member values,” Millerchip said.
Costco has lowered prices across its product categories, including food, fresh merchandise, and non-food items.
Some of those price cuts are already visible on Kirkland Signature products.
Costco said the broader tariff-refund investments included everyday products such as produce, meat, and beverages, as well as home furnishings and hardware.
Higher memory costs pressured consumer electronics, while higher meat prices were largely offset by lower egg and dairy prices.
Costco has not announced a new special dividend
Another question remains unanswered.
In my earlier Costco earnings preview, BofA said the company’s growing cash pile could prompt another special dividend in the next several quarters.
Costco last issued a special dividend in 2024.
The company ended fiscal 2026 with $20.21 billion in cash and cash equivalents, up sharply from $14.16 billion a year earlier.
But Costco did not announce a special dividend with its fourth-quarter earnings, and the company has not issued a newer dividend announcement since the report.
The most recent dividend declaration came in July, when Costco’s board approved its regular quarterly cash dividend of $1.47 per share.
So for now, BofA’s special-dividend call remains a possibility rather than a company announcement.
Costco also has plenty of uses for its cash.
Management expects capital spending of roughly $7.5 billion in fiscal 2027 as it accelerates warehouse openings and continues investing in its supply chain.
Despite the growth, Wall Street increasingly wants to know whether Costco can keep expanding that customer base.
And whether it can grow fast enough to justify the price investors are being asked to pay.
Related: Popular restaurant chain closes nearly all locations in 2026