Why E-Invoicing Could Rewire the GCC Economy
Dubai has nailed its colours to the mast. By 2033, the emirate’s bicentennial, it wants to be among the world’s top three cities to live, work and invest, and to have doubled the size of its economy. Those aims, gathered under the Dubai Economic Agenda (D33), are not marketing slogans. They are a policy programme built on digital public infrastructure, regulatory modernisation and the ruthless removal of friction from commerce. In short, scale through standards. Identity, payments, data exchange and e-invoicing rails are being treated as core infrastructure, not optional extras.

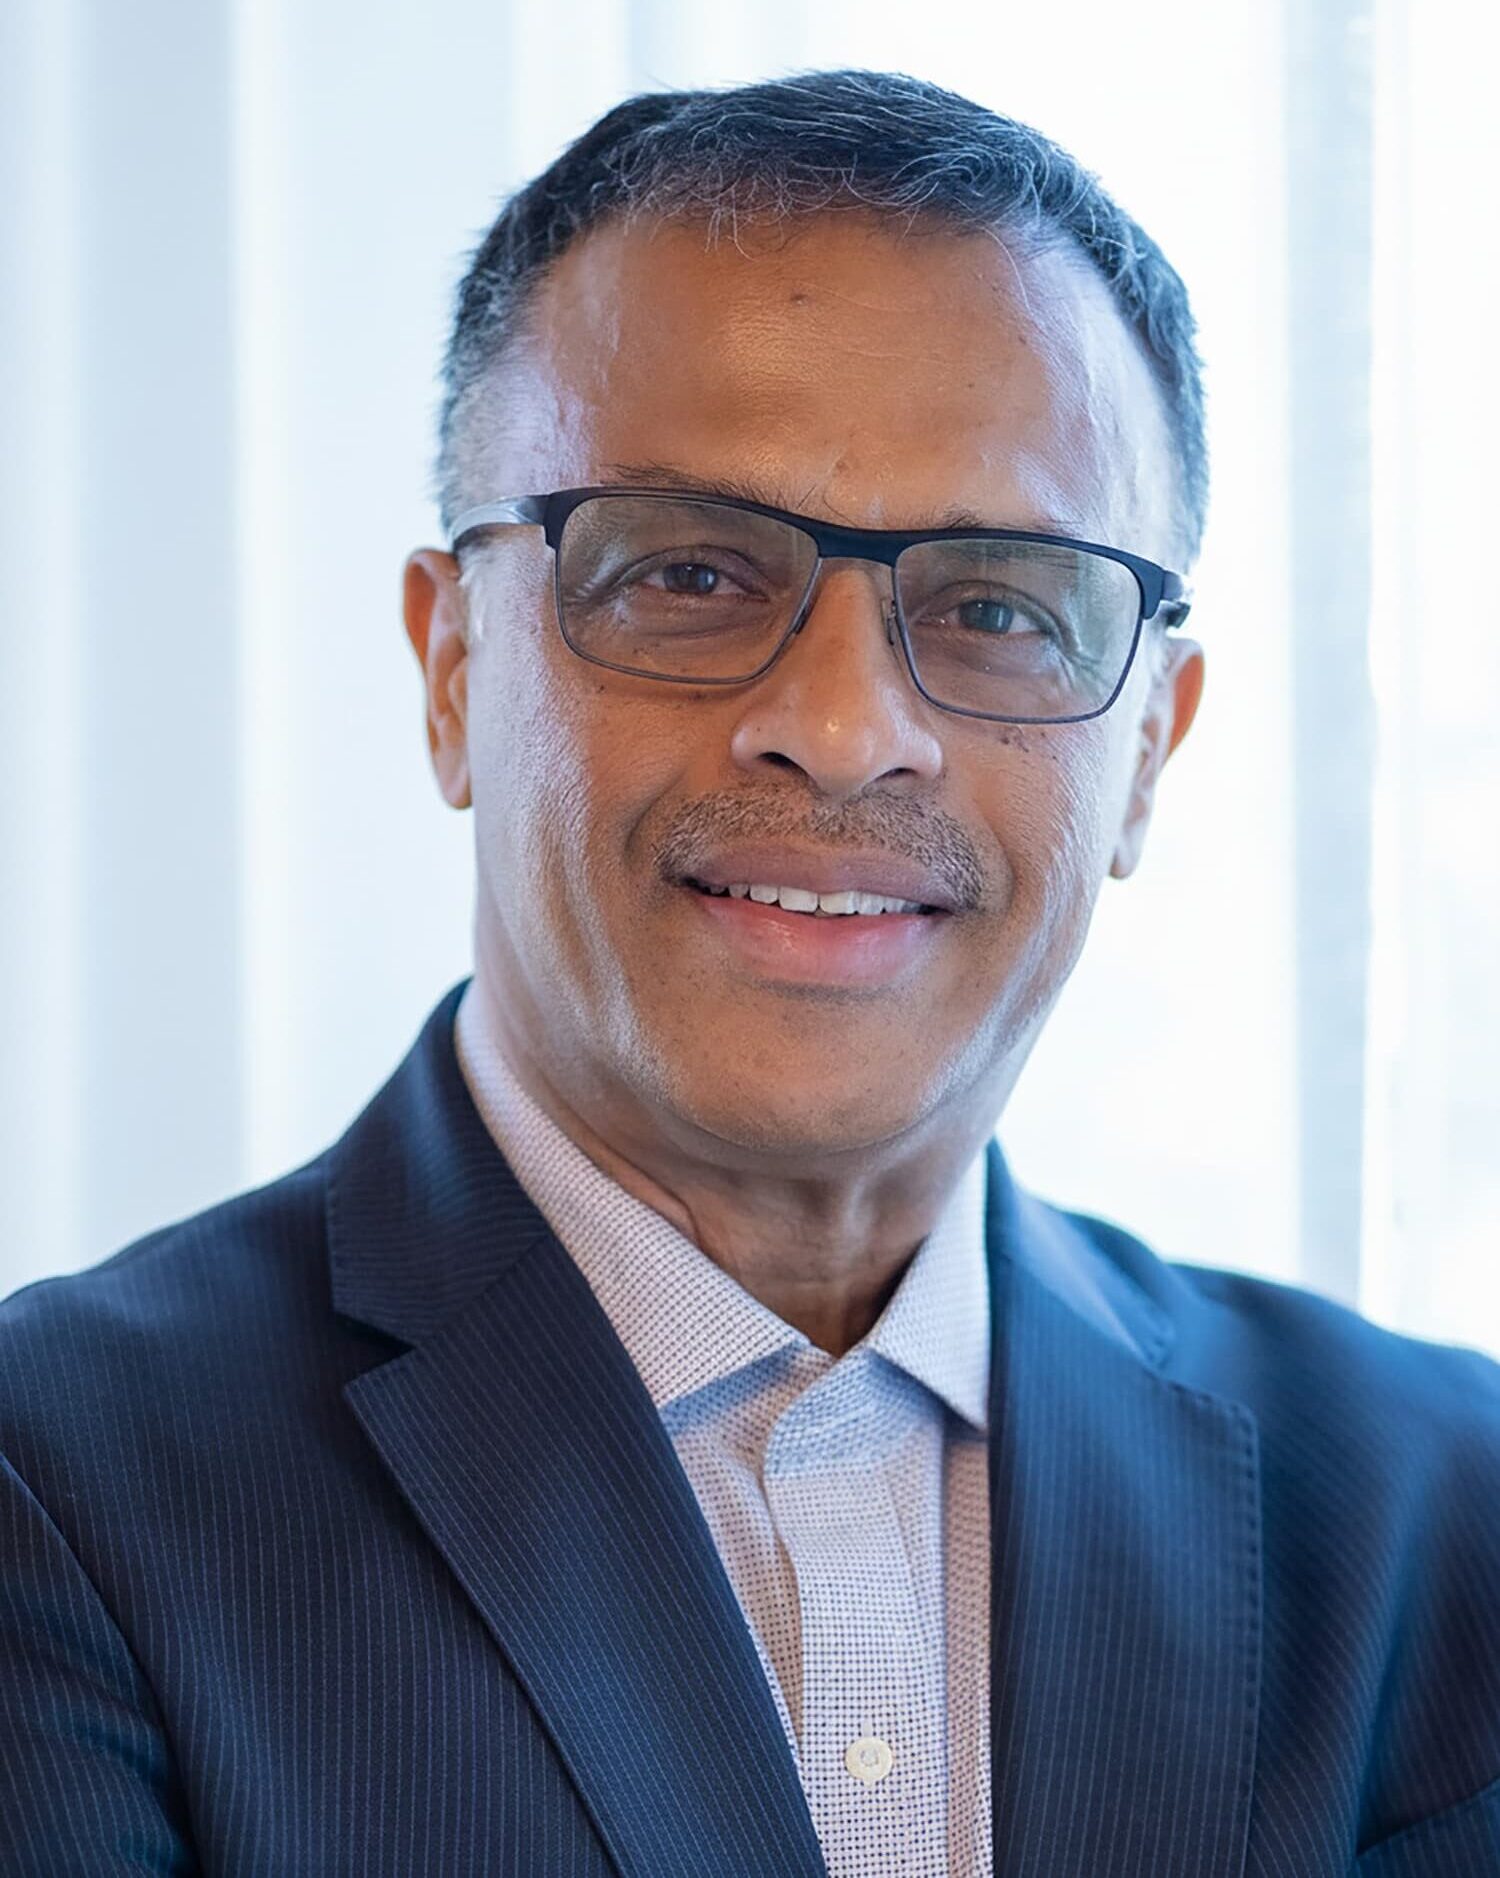
Nanda Kumar is the CEO and founder of SunTec Business Solutions, which builds pricing, billing and revenue-management systems for banks and large enterprises. The views that follow are his own, presented as a contributed opinion piece.
Across the GCC, the most prosaic artefact in business, the invoice, is being turned into national infrastructure. Saudi Arabia led with ZATCA’s two-stage regime: a Generation phase that forces structured invoices, and an Integration phase that connects taxpayers to the authority’s systems. The UAE has followed with Ministerial Decisions 243 and 244 of 2025, which define what an electronic invoice is, prescribe accredited service providers, and set a phased timetable that moves large taxpayers first, then smaller firms, and finally government entities through 2027. When every transaction is born digital, in a machine-readable format, compliance becomes a by-product and data becomes a public good. E-invoicing stops being a narrow tax project and becomes part of the country’s commerce operating system.
Why does this matter? Because invoices sit at the edge where the real economy touches the financial system. Digitised at source, they tighten VAT control and reduce reconciliation theatre. They compress working-capital cycles across both accounts receivable and accounts payable by standardising confirmations, credit notes and settlement. They also produce policy-grade telemetry, anonymised signals on sectoral activity, SME health and cross-border trade, that help officials target incentives and measure impact. That is how the UAE’s future-ready government vision turns from aspiration into instrumentation: a real-time, fully digital, continuously compliant view of economic life.
The policy ambition is not simply to digitise paperwork, but to engineer a frictionless yet highly secure economic environment. In real-time, event-driven systems, legitimate activity flows with less friction because rules are embedded in the rails. Anomalous patterns are flagged instantly, not months later in an audit file. Law-abiding citizens and firms benefit from fewer checks and faster decisions, while bad actors stand out against a background of standard, trustable data. The same logic that underpins smart urban infrastructure is being applied to commerce.
Regulation is catching up with ambition. In September the UAE issued a consolidated banking law, Federal Decree-Law No. 6 of 2025, which folds banks, insurers and a wider constellation of financial actors under a single supervisory perimeter at the Central Bank. The law adds an early-intervention and resolution toolkit, including administrators, bridge institutions, temporary stays and moratoria. It raises penalty thresholds, formalises a digital money and payments system aligned to the CBUAE‘s FIT agenda and the Digital Dirham, and, most crucially, shifts from licensing institutions to licensing activities irrespective of the medium, technology or form. In effect, it widens the perimeter to include API platforms and decentralised applications without sacrificing prudence, laying the legal backbone for open banking and data-led markets.
Put together, D33, e-invoicing and the new banking law point in the same direction: information velocity. If every transaction throws off standard, trustworthy data, and if supervisors, banks and enterprises are equipped to act on it in real time, then firm formation, trade finance and cross-border flow all speed up. Export-promotion agencies and free-zone platforms can see pipelines earlier. Lenders can price risk with more granularity and reward policy-aligned behaviour, from on-time payments to greener procurement. As open-banking frameworks deepen across the region, the same data streams will power safer, more personalised products at the point of need. The region’s growth story becomes less about megaprojects and more about the compounding effect of clean, connected micro-events.
My view, shaped by three and a half decades of working with banks and large enterprises, is simple: winners treat regulatory data as production capital. When compliance becomes real-time and data-rich, customers can see what they are charged and why, supervisors get evidence on demand, and institutions can move from periodic repricing to event-driven offers anchored in observed behaviour. Transparency and traceability lower risk. Lenders make contextual decisions on the back of actual cash-flow events rather than static snapshots, supervisors see stress early, and treasurers see their own business in finer grain. This is the shift from meeting the rule to monetising the signal. It demands new operating models in which pricing, billing and analytics sit alongside the core as a configurable control-plane. Product teams change rules weekly, not yearly, and finance closes without heroics because evidence is born structured.
The UAE’s new regime will reward this posture. Activity-based licensing under the new banking law reduces regulatory arbitrage while encouraging responsible innovation in payments, digital money and embedded finance. E-invoicing makes the canonical record of usage which, mapped to products, entitlements and settlement rules, yields cleaner bills, fewer disputes and faster cash. Make that the spine for pricing, billing and deal management, and organisations gain a continuous, explainable view of their commercial reality. D33’s connectivity ambitions then have the data they need, with customs, credit bureaus, export desks and free zones reading from the same ledger of facts.
By Dubai’s bicentennial in 2033, the economies that treat compliance data as growth capital will move faster, lend smarter and export more. The GCC’s wager is pragmatic: build trustable data at source through e-invoicing and an activity-based supervisory regime, extend that foundation with open-banking and digital-money rails, and let the rest of the digital economy compound. D33 provides the canvas, the new banking law stretches it taut, and e-invoicing supplies the first brushstrokes. The rest is execution, turning a policy arc into operating reality, one structured transaction at a time.
The post Why E-Invoicing Could Rewire the GCC Economy appeared first on The Fintech Times.