Secure Trust Bank Joins Hargreaves Lansdown Active Savings Platform
Secure Trust Bank has signed a distribution agreement with Hargreaves Lansdown that will make its savings products available through the HL Active Savings platform, the bank announced on 10 August 2026. The deal marks Secure Trust Bank’s first deposit aggregator relationship and extends its funding channels beyond direct sales and comparison website listings.

The bank’s Access Account will be available to HL Active Savings customers from the outset, with Access ISAs, Fixed Rate Bonds and Fixed Rate Cash ISAs expected to follow. Secure Trust Bank did not set a timeline for the wider product rollout or disclose target deposit volumes through the channel.
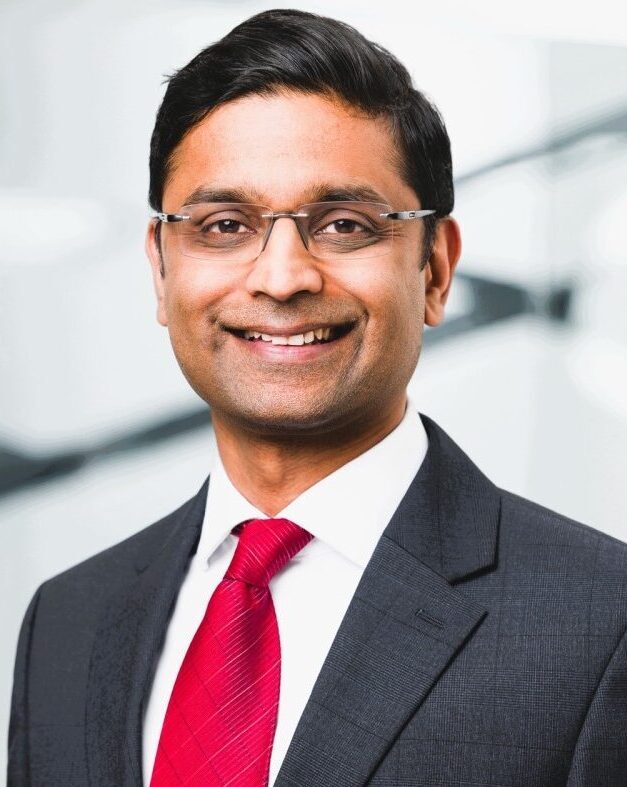
Rajat Mehta, savings director at Secure Trust Bank, who joined at the end of 2025, said the move was “fundamentally about diversifying our distribution and strengthening our funding model,” adding that access to an established platform alongside existing direct and comparison channels would support “the efficient management of our cost of deposits.”
The funding rationale
The deposit aggregator model has become a mainstream instrument for retail banks seeking to manage their cost of funds with more precision. Rather than relying on a single sticky direct-to-consumer channel, banks that distribute through platforms such as HL Active Savings can dial up or down deposit inflows by adjusting rates or product availability, giving treasury functions a more granular lever over the liability book. For a bank the size of Secure Trust Bank, which serves a focused lending portfolio across real estate finance, commercial finance and V12 Retail Finance consumer lending, access to a broader and more price-sensitive depositor base can smooth the match-funding of its loan book without materially increasing the cost base of customer acquisition.
Hargreaves Lansdown administers approximately £200 billion in client savings and investments across more than two million customers. Its Active Savings platform already hosts more than 30 banks and building societies, positioning it alongside comparable aggregators such as Raisin UK and Flagstone in the cash savings distribution market. For smaller or mid-tier banks, these platforms offer reach that would otherwise require significant marketing expenditure to replicate.
Market context

The UK cash savings distribution landscape has consolidated meaningfully since the period of rising interest rates that began in 2022. Platforms that aggregated savings products benefited from rate competition as banks fought for retail deposits during a period of tightening monetary policy. With the Bank of England‘s base rate having eased from its 2023 peak, the margin calculus for deposit-gathering has shifted, but demand from savers to compare and switch products remains elevated relative to the pre-2022 baseline.
For Secure Trust Bank, the partnership is as much a structural funding decision as a distribution one. The bank released its interim results for the period to 30 June 2026 on 13 August 2026, providing an updated view of its deposit position, funding mix and net interest margin. The terms of the HL relationship, including any exclusivity provisions or minimum volume commitments, were not disclosed.
Aman Rai, head of bank partnerships at Hargreaves Lansdown, noted that Secure Trust Bank’s addition strengthens the platform’s savings offering and gives clients greater choice when managing cash savings, a standard commercial framing consistent with the platform’s positioning as a one-stop savings marketplace.
The post Secure Trust Bank Joins Hargreaves Lansdown Active Savings Platform appeared first on The Fintech Times.