The CRE Doom Headlines Are Back But the Data Is Less Scary Than It Sounds
Negative headlines about commercial real estate are back. Bloomberg reported this week that the office crisis is shifting to CMBS investor losses, and The Wall Street Journal warned that apartment landlords have a $2 trillion debt problem that is only getting worse. Both stories arrived days after the Federal Reserve raised its benchmark interest rate by 25 basis points to a target range of 3.75%-4%, its first increase since 2023. Together they describe an industry where the strategy of waiting for lower rates has run out of road.
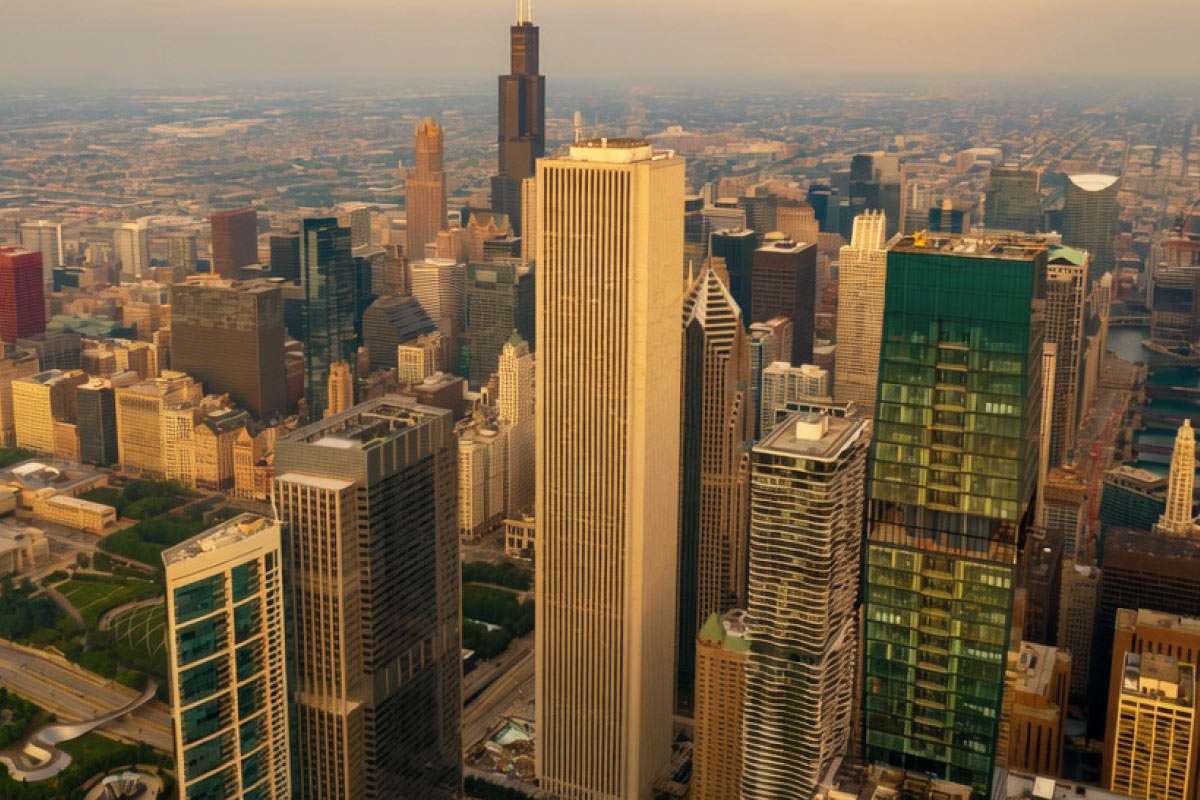
Bloomberg anchors its story in Chicago’s Aon Center. The 83-story tower sold for $712 million in 2015 and was appraised in May at $195 million. When its loan came due in July, the owner asked for a three-year extension and the special servicer’s response was “unequivocally denied.” Office CMBS delinquency reached 12% last month according to Trepp, above the levels that followed the 2008 financial crisis. About $64 billion of office CMBS debt matures this year and next, and almost $40 billion of it is delinquent, in default, or on a watchlist. Josh Morris, partner in global real estate at Davidson Kempner Capital Management, said hope that rates would decline died sometime between last year and this year.
The Journal’s apartment numbers are just as large. Multifamily owners face more than $1.8 trillion in maturing debt over the next decade, with about $757 billion coming due through 2028 and nearly $300 billion this year alone, according to the Mortgage Bankers Association. Many of those loans were written at around 3% in 2020 and 2021 and now have to be refinanced at roughly twice that. The CMBS delinquency rate for multifamily jumped from 1% in October 2023 to 7.1% this year, according to Morgan Stanley. Even the largest owners are exposed. Blackstone defaulted on a $90 million loan for a North Dallas apartment building it bought in 2021.
These are real problems, but they are not new ones. Office delinquencies have been setting records for more than a year, and the apartment maturity wall has been reported on for at least two. What changed is the rate backdrop. The Fed’s new range still sits well below the 5.25% to 5.5% peak of the last tightening cycle. The 10-year Treasury moved back to its highest level since 2007 after the Fed decision, which is close to where it peaked in late 2023, a level the market absorbed without a systemic break. The 2008 crisis was a solvency problem inside the banking system. The post-pandemic stress was a sudden demand shock paired with the fastest rate increases in decades. A quarter-point hike on top of rates the industry has lived with for three years is a serious headwind for leveraged borrowers. It is a different kind of event.
The banking data does show a system under strain. The banking industry finished the second quarter with a return on assets ratio of 1.37 percent, domestic deposits increased for the eighth consecutive quarter, and asset quality metrics improved. The non-owner-occupied CRE past-due and nonaccrual rate for banks with assets greater than $250 billion declined for the seventh consecutive quarter to 3.08 percent, below the recent peak of 4.99 percent in third quarter 2024. The reserve coverage ratio increased to 172.7 percent. Smaller lenders deserve more attention. The reserve coverage ratio at community banks declined to 145.6 percent as noncurrent loans outpaced new reserves. Even the Journal notes that banks have stronger balance sheets than they did several years ago, which gives them room to take back properties rather than be forced into fire sales.
The apartment debt also looks different once you see who holds it. The agencies hold $1.2 trillion of apartment debt, half of the entire market, and almost none of it is maturing. Real Capital Analytics estimates outstanding and potential multifamily distress at $115.3 billion, which equals about 5.7% of the $2.5 trillion multifamily debt market. Office losses are real for the bondholders taking them, and Bloomberg cites a Deutsche Bank report showing distressed office sales closing 20% below recent appraisals. But office mortgage risk is widely dispersed among global investors, which diminishes the potential threat to the US banking system. Losses spread across insurers, bond funds, and private credit vehicles hurt. They do not concentrate in a way that brings down institutions.
Both articles end in the same place, saying that we might start to see mass delinquencies that would create a buying opportunity for those with capital to invest. I would not dismiss the risk of rates climbing further, the majority of the Fed expecting another hike this year. But while there might be some repricing going on, I imagine that most buildings are being underwritten very similarly to how they were before the last rate hike. But that kind of thinking often doesn’t get the same attention as a doomsday tale.
The post The CRE Doom Headlines Are Back But the Data Is Less Scary Than It Sounds appeared first on Propmodo.