VOL REPORT: FLEX Options Flex Muscles
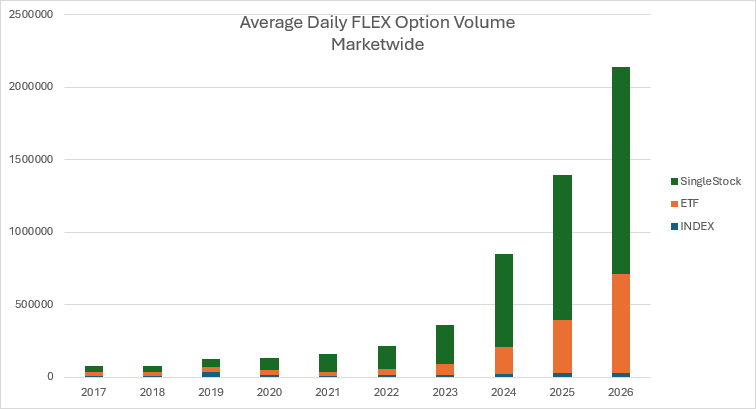
Flexible Exchange options – customized, ‘off menu’ contracts that for many years were primarily arranged by appointment – have existed since the early 1990s. The expansion of FLEX beyond just a niche market has only been in recent years, driven by electronic trading and the tie-in with exchange-traded funds.
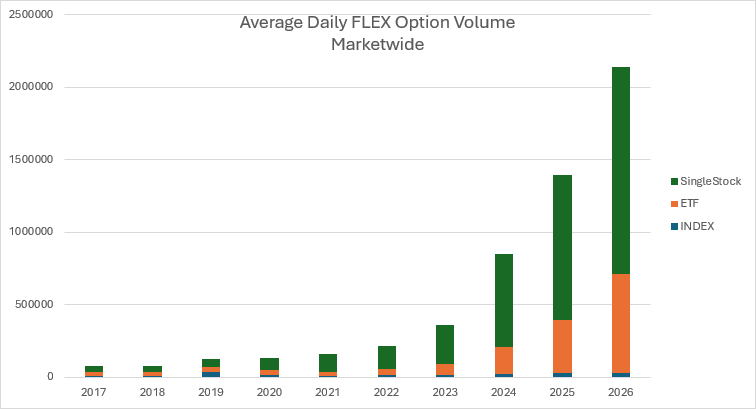
Average daily volume for FLEX options has been 2.15 million contracts so far in 2026, or 2.7 percent of listed ADV, according to Cboe Global Markets data. FLEX ADV is up from 1.4 million contracts in 2025 and just 160,000 contracts five years ago.
“They didn’t trade very much at first,” said Henry Schwartz, Vice President, Market Intelligence at Cboe. “You’d have a couple people walking around on the floor looking for someone who might be interested in doing something, but it was tough to get anybody to make the effort to trade FLEX options. Now, they’re tradable electronically, which makes it much more efficient to execute.”
A seminal moment for FLEX options came in 2018, when Innovator ETFs launched the first defined outcome ETFs, which tracked the S&P 500 Index but with built-in upside caps and downside buffers. With custom expiration dates, tailored strike prices, and precise payoff structuring, FLEX options are the foundational building blocks that effectively put the ‘defined outcome’ in defined outcome ETFs.
It took a few years to get traction, but FLEX options in defined outcome ETFs are firing on all cylinders. “There’s a community of liquidity providers who are active in listed options, which is how you get liquidity in FLEX options,” Schwartz told Traders Magazine. “The ETF creators are going to the same participants who are trading options on SPX, or Tesla, or Apple … And that liquidity community is ready to trade FLEX options just as easily as standard listed options.”
Bill O’Keefe, Director, North American Derivatives at Cboe, noted that there are currently over 960 options-based ETFs with roughly $342 billion total under management, up from about 400 ETFs and $122 billion a few years ago. “That’s massive growth,” he said.
O’Keefe cited flexibility, workflow simplification, and precision of outcomes as primary appeals of FLEX options.
For instance, Cboe’s FLEX Delta Adjusted At Close (DAC) – limit orders for FLEX options that execute intraday and receive a delta-adjusted price based on that day’s official closing price of the underlying security or index value – obviate the need to calculate multiple options spreads, each with multiple legs, at the 4 pm close. Also, certain FLEX ETFs are cash settled, meaning the financial difference between the strike price and the settlement price is paid or collected in cash, with no shares left over.
“Innovation is happening faster in the FLEX world than it is in the listed world,” Schwartz said. “I think we’re going to continue to see more creativity going into the whole structured product and defined outcome ETF universe.”
Currently, the largest defined outcome ETF is the FT Vest Laddered Buffer ETF (BUFR), with more than $10 billion in assets under management, according to ETF.com. One of the smallest is the Fortuna Hedged Bitcoin ETF (HBTC), which has $828,000 and is long BTC and short USD.
The rapid growth in FLEX options is part of a broader market-structure evolution, according to Robert Romano, Head of Structured Products Americas at interdealer broker TP ICAP.
“The wrappers may differ: FLEX options, ETFs, warrants or certificates, but the direction is similar,” Romano wrote in a LinkedIn post last month. “Moving structured exposures toward listed infrastructure that can provide greater transparency, capital efficiency, liquidity, operational simplicity and digital distribution.”
Romano continued: “Perhaps the real trend is not simply the growth of FLEX options. It is the gradual digitalization and industrialization of structured investing, with investors increasingly focused on the desired payoff while exchanges, asset managers and issuers compete to deliver it through the most efficient wrapper.”
(VOL REPORT is a Traders Magazine – Cboe Global Markets content collaboration that covers volatility and its implications for market participants and operators.)